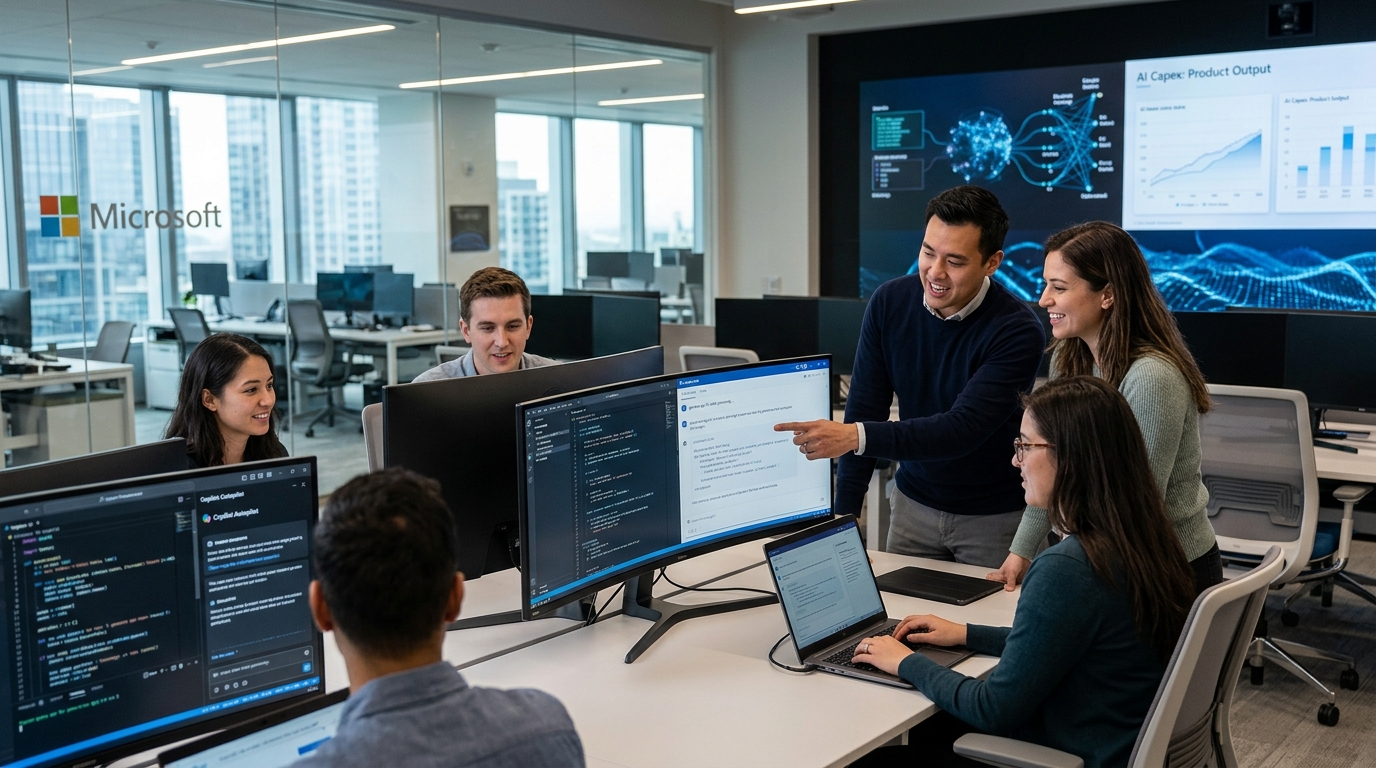
Microsoft has spent the better part of two years defending a capital expenditure bill that made investors nervous. On Friday, it finally showed them what the money is for.
Microsoft revamped its Copilot app on September 25, building the update around three new capabilities: Home, Code, and Autopilot. Code lets users generate apps, dashboards, and automations from plain-language prompts, with rollout beginning in the company’s Frontier program in the coming weeks. Autopilot, the persistent agent that Microsoft previously introduced as Scout, lives in a customer’s tenant with its own identity, memory, computer, and workspace, and it is expanding to private preview at the end of the month. The company is also integrating Word, Excel, and PowerPoint into the Copilot experience so users can create or update real, editable files from inside Copilot.
The Dow Jones Industrial Average gained 478.64 points, or 0.93%, to 51,828.62 on Friday. Microsoft jumped 4.1% and added 120 Dow points after rolling out the rebuilt Copilot app. That single stock did more than a quarter of the index’s work.
Why the Product Design Matters to Investors
The distinction between a chatbot and what Oppenheimer’s Brian Schwartz is now calling an “AI operating system” is not semantic. Schwartz noted that operating systems and platforms drive higher user engagement, create more monetization opportunities, and build greater customer stickiness. That is the difference between a tool people occasionally open and infrastructure they cannot remove.
Microsoft’s $115.9 billion fiscal 2026 capital expenditure total has kept a lid on the stock for months, with investors demanding proof that the spending would translate into durable revenue. A critical tension has been building: while Azure AI revenue surged, Microsoft 365 Copilot still faced questions about conversion from the broader Microsoft 365 installed base. The rebuilt platform, with its agent layer and native code generation, directly targets that conversion problem.
The Azure Equation
The investment thesis ultimately clears or fails on Azure. Microsoft said Azure revenue surpassed $100 billion in fiscal 2026, the first time it has done so. The question is whether growth can keep accelerating from an already high base.
Schwartz calculated that Azure’s constant-currency growth could land near 46% for the current quarter, topping Microsoft’s own guidance, with growth potentially climbing toward 50% the quarter after. If Azure growth approaches 50% while operating at a scale exceeding $100 billion, Schwartz said that could drive a rerating of Microsoft stock. Oppenheimer raised its price target to $570 from $515, keeping its Outperform rating in place. Cantor Fitzgerald recently lifted its target to $608 from $522, citing strong growth fundamentals and steady capital expenditure guidance.
Bull Case, Bear Case
Customer demand, now spreading well past the handful of frontier AI labs that once dominated it, is expected to keep outstripping available capacity through year-end. That demand signal, combined with Copilot’s new agent and coding layers unlocking fresh monetization paths, gives the bull case genuine substance.
The risks are real, too. A pull-forward of enterprise IT spending in the second half of 2026 could moderate Azure and Microsoft 365 commercial revenue growth heading into 2027, and cloud margins could compress if capital expenditure efficiency declines. Microsoft has not disclosed pricing details for usage-based charges tied to Code or Autopilot, nor a specific general-availability date beyond the upcoming Frontier and private-preview rollouts. Until those numbers are public, monetization remains a projection.
What to Watch Next
Microsoft’s fiscal first-quarter earnings report is the next hard data point. Azure growth for the September quarter will either validate Schwartz’s 46% estimate or expose it. Watch also whether enterprises move Autopilot out of private preview and into production use at scale. Commercial remaining performance obligation surged 84% year-over-year to $678 billion, suggesting long-term commitments are already in place. The real question is whether Copilot converts that backlog into seat growth.
Friday’s move was a product reaction. The rerating Oppenheimer described requires Azure results to match the ambition of the announcement.
 Rising Star Stocks