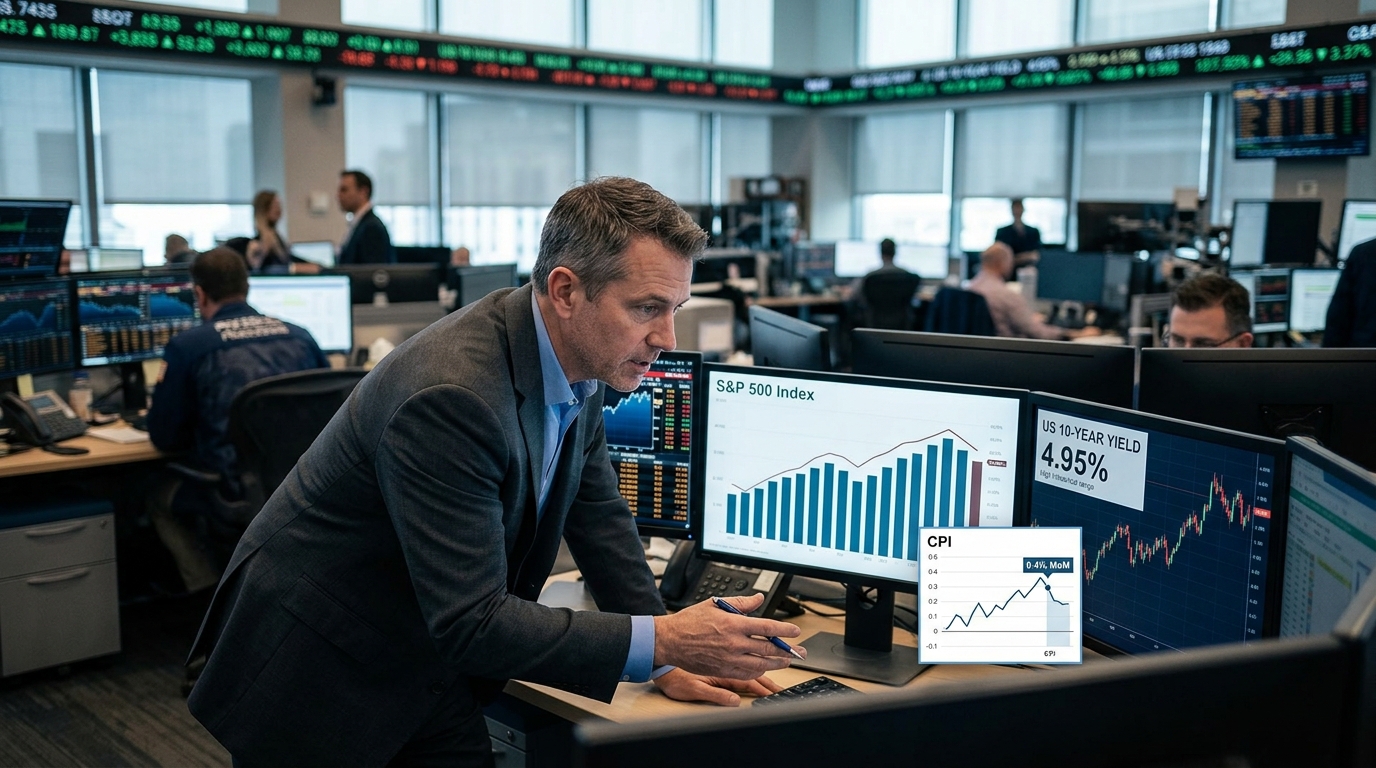
Friday’s CPI report removed whatever doubt remained. The consumer price index rose a seasonally adjusted 0.4% for the month, putting the 12-month increase at 3.4%. Headline came in exactly on forecast. The market-moving number was underneath it: stripping out volatile food and energy prices, core CPI posted a 0.3% monthly gain, 0.1 percentage point higher than forecast. That single tenth of a percent was enough to seal the meeting. Markets are now pricing in a roughly 87% chance the Fed raises interest rates by 25 basis points at the FOMC meeting next week, up from 72% a day ago and 50% a week ago.
The hike itself is no longer the story. Wednesday’s decision moves the fed funds rate to 3.75%-4.00% and arrives alongside a fresh Summary of Economic Projections. For traders, the SEP matters more than the rate move itself, and here is why: the June dot plot was already provocative. Reuters reported in June that nine policymakers projected at least one hike, with six even suggesting multiple hikes could be in the offing. Warsh withheld his own dot entirely, saying he has “refrained from offering any projections,” consistent with his long-held views. Wednesday’s updated projections will be the first since August CPI, a jobs report that added 162,000 nonfarm payrolls, well above forecasts near 55,000, and oil prices pushing above $100 a barrel. The pain trade is a median dot that clusters above 4.25% for year-end, implying another hike before December is more likely than not. Futures markets are already pricing a gradual increase to about 4.1% by December and roughly 4.5% by September 2027. A dot plot that validates that path keeps the pressure on equities and long-duration assets for weeks, not days.
The Technical Picture Has Already Deteriorated
The S&P 500 dropped below its 50-day moving average Thursday for the first time since late July. That matters because the last time the index broke that level, it recovered quickly on peace hopes and a dip in oil. Those conditions no longer exist. The S&P ran into resistance near a record high around 7,800 before pulling back to test the 50-day EMA around 7,600, where it has recovered slightly. A hold there is the bull case into Wednesday. A close below 7,600 opens 7,470 and, below that, 7,300.
The 10-year yield finished September 11 at 4.96%, while the 2-year note ended at 4.63%. That near-inversion is a live issue for anything duration-sensitive. Growth stocks, REITs, and high-multiple tech names face renewed compression if Wednesday’s press conference signals Warsh is not done. His stance has been consistent: “While this summer’s inflation readings were better than expected, they do not tell me that underlying trends have meaningfully improved.”
Sector Rotation: Who Wins, Who Loses
Information technology, consumer discretionary, and materials stocks have borne the brunt of recent declines, while utilities have held up best on the week. That rotation makes sense and is likely to persist through at least Wednesday’s announcement. Energy benefits directly from $100-plus oil and passes inflation through to earnings. Financials, specifically banks with variable-rate loan books, see net interest income improve with each 25bp move. Utilities deserve more scrutiny: they carry rate-sensitive valuations, and a hawkish dot plot could reverse this week’s defensive bid quickly.
Energy prices have continued to rise amid the Iran conflict, with diesel hitting $6 a gallon. Because diesel powers the trucks and railroads that transport goods, the surge could ripple through the economy as businesses hike prices to offset higher costs. That pipeline argues for staying long energy into the meeting, not as a trade on the Fed’s decision, but as a hedge against the scenario where Warsh signals more than one additional hike.
Trader’s Action Plan
The meeting decision Wednesday afternoon is the first event to trade around, but Warsh’s press conference immediately after is the one that sets the tone for the next six weeks. The question he cannot duck: how many more hikes does this committee have in it? One strategist sees a scenario where a series of hikes over the next six to nine months makes the overnight rate meaningfully higher, and argues that what matters most is the Fed establishing credibility against inflation if it continues to rise.
For the SPX, the levels that matter are 7,600 as support and 7,750 as near-term resistance. A dovish hike, where Warsh signals Wednesday is likely a one-and-done, probably takes the index back toward 7,750 by end of week. A hawkish hike with a dot plot projecting another move in October or December tests 7,470 and potentially 7,300. The 10-year approaching 5% is the second trigger to watch. If the Fed holds and Warsh cannot give a solid reason, there could be a test of the 5% yield on the 10-year Treasury regardless. Position size accordingly. This is an event where being right on the direction but wrong on the magnitude of the move is the most common outcome.
 Rising Star Stocks