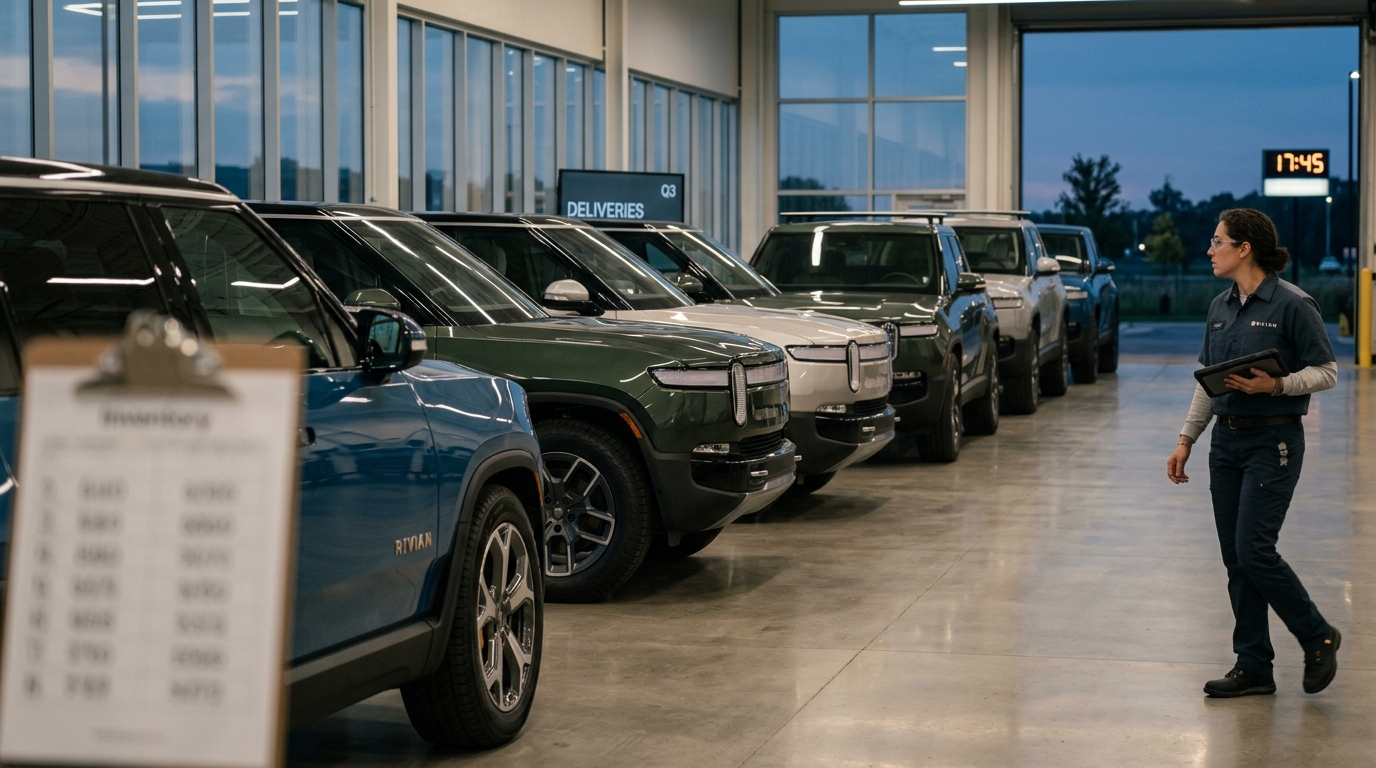
Rivian posted a record 19,248 deliveries in the third quarter, up about 46% from a year earlier, and the market sold the stock anyway. Shares fell roughly 3% after Rivian kept its full-year guidance unchanged despite reporting deliveries above expectations. That reaction tells you what investors are really waiting for: not another strong volume number, but the first quarter where volume turns into automotive profit.
Rivian began delivering the R2 to external customers on June 9, making the third quarter the first to include a full three months of the model. Deliveries have climbed each quarter this year, from 10,365 in Q1 to 12,194 in Q2 to 19,248 in Q3. The 58% sequential surge is the steepest single-quarter jump in the company’s history. Through three quarters, Rivian has now delivered 41,807 vehicles.
The Volume Math
The R2 is the engine behind the ramp, but Rivian does not break out deliveries by model. Analyst estimates placed R2 deliveries somewhere around 8,400 for the quarter, with commercial vans contributing roughly 5,900 and the R1 around 4,300. If those estimates are close, the R2 already accounts for nearly half the quarter’s volume in its first full period of production.
What that volume does to per-vehicle economics is the crux of the October 29 story. In Q2, Rivian delivered 12,194 vehicles on $1.658 billion of revenue and the automotive segment still posted a gross profit loss of $36 million. That quarter absorbed approximately $100 million of incremental costs from ramping R2 production. With output nearly 60% higher in Q3 and the ramp costs partly behind the company, the fixed-cost leverage argument finally has volume to work with.
Rivian has said it expects to achieve a positive automotive gross profit exit rate during 2026, with its Normal, Illinois plant moving to two shifts during the second half of the year to support higher output. Q3 will still absorb a full quarter of R2 ramp costs and second-shift labor expenses, while Q4 should benefit from higher volume and fixed-cost leverage. That sequencing means Q3 may not yet be the positive quarter, but it should narrow the loss materially.
What the Software Business Buys
The reason Rivian can absorb negative automotive margins at all is the Volkswagen joint venture. Software and services generated $515 million in Q2, with $308 million flowing from the Volkswagen partnership, and threw off $215 million of gross profit. That cushion has allowed Rivian to fund the R2 ramp without a dilutive equity raise, but it is not a permanent substitute for a vehicle business that makes money.
Bull and Bear
The bull case is straightforward: only the pricier Performance trim of the R2 is currently available, meaning a lower-cost standard variant arriving later could expand the addressable market further. Guidance of 65,000 to 70,000 vehicles for the full year has been reaffirmed, requiring somewhere between about 23,200 and 28,200 deliveries in Q4. A second shift running through the final stretch makes that achievable.
The bear case is that automotive gross profit has been negative in every quarter this year. And while Rivian did report $1.658 billion of revenue and $179 million of consolidated gross profit in Q2, the company remains loss-making at the bottom line. Volume is climbing, but the question of whether R2 is structurally cheaper to build than R1 at scale remains open until the financials say so.
What to Watch on October 29
The number that matters most is automotive gross profit and the direction of per-vehicle economics. If Q3 shows a narrowing loss, the Q4 case for turning positive becomes credible. If the loss holds near Q2 levels despite 60% more volume, it raises genuine questions about R2’s cost structure at this stage of the ramp. Rivian releases full Q3 financial results on October 29 after market close. That is the session where the delivery record either becomes a turning point or just another impressive number on the way to an answer that is still months away.
 Rising Star Stocks