Editor’s Note: Former $900 million hedge-fund manager Larry Benedict completed 20 consecutive years without a losing year and took his fund into the top 1% worldwide. Today, he says one long forgotten American giant already possesses what Elon Musk needs to bring his $119 billion plan to life. Click here to get the ticker completely free or read more below.
Dear Reader,
Nvidia CEO Jensen Huang issued a blunt warning about Elon Musk’s new $119 billion plan.
He says it will be “extremely hard” to pull off.
For most investors, that sounds like a reason to stay away.
But Wall Street legend Larry Benedict sees a rare opportunity forming in one particular ticker.
It’s a once-great American company that Wall Street dismissed after years of setbacks.
And Larry says it could be the key to potentially making all the money you need, in any market.
That is a bold call… but if anyone has earned the right to make it, it’s Larry…
You see, between 2004 and 2012 alone, his hedge fund generated more than $274 million in audited net income.
And during his career, Larry managed more than $900 million. .
He built that record by recognizing market-moving opportunities before Wall Street caught on.
Now he says this could be one of them.
Even a small move in its shares could give you a shot at doubling your money with the right strategy.
Regards,
Lauren Wingfield
Managing Editor, The Opportunistic Trader
P.S. Whether Elon succeeds with his plan or not, Larry believes you will have chances to profit. But you need to be positioned before November 30 – or risk missing out completely.
Tandem’s Insulin Pump Just Beat Its No. 1 Complaint
For years, one line followed Tandem Diabetes Care into every analyst note and competitor pitch: Omnipod is tubeless and yours is not. That line just expired.
What Changed Friday
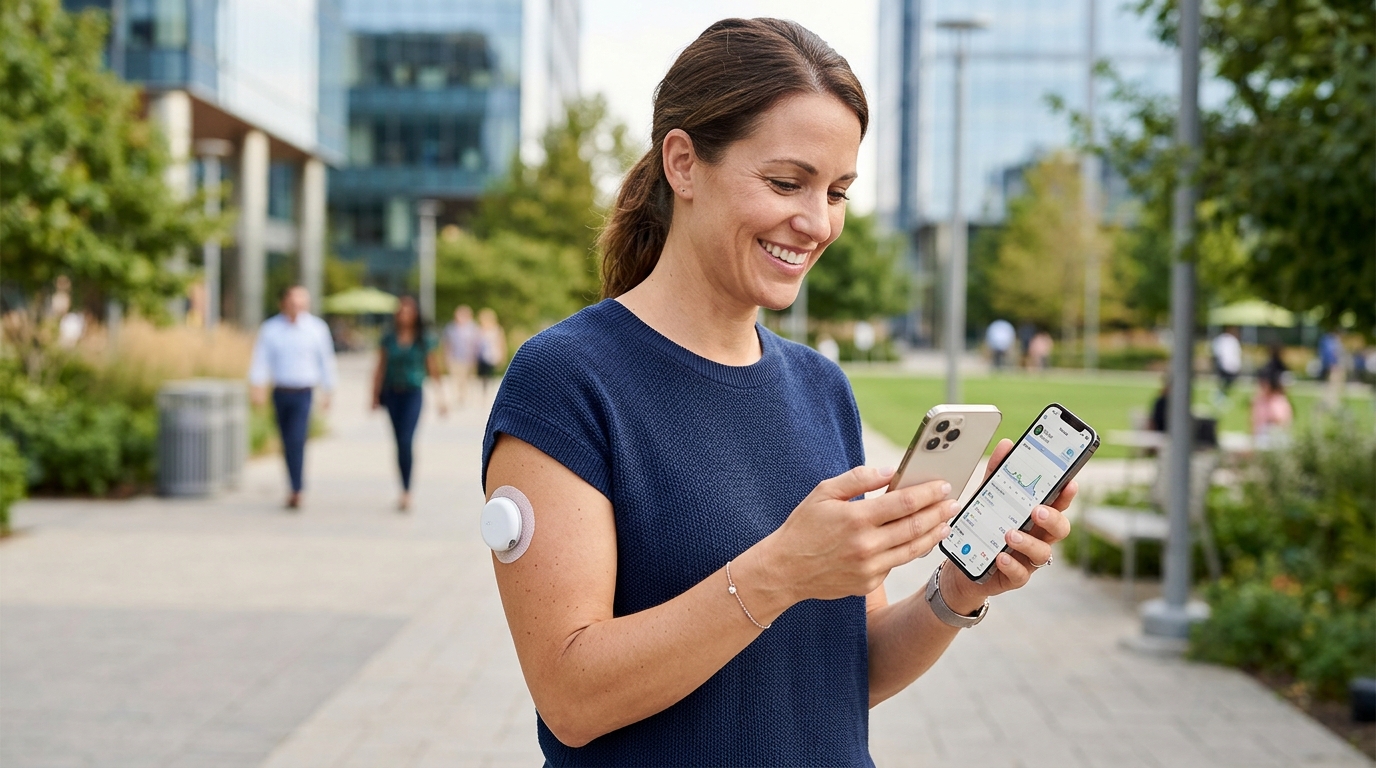
On November 12, Tandem received 510(k) clearance from the FDA for the Tandem Mobi, which the company describes as the world’s first and only tubeless automated insulin delivery system with up to seven days of wear. A new cartridge and infusion set convert the existing pump body into a skin-worn device. Current in-warranty Mobi users will not need a new pump, just the compatible accessories. That is a meaningful detail: Tandem is not asking its installed base to start over.
The Mobi’s new tubeless wear time of up to seven days beats Insulet’s Omnipod 5, which tops out at three days. The tubed option remains available. Tandem says Mobi is now the only insulin pump cleared for both tubed and tubeless wear options. That flexibility matters to prescribers who cover a wide range of patient preferences, from active users who want on-body discretion to others who prefer the larger cartridge capacity of a traditional setup.
A full U.S. commercial launch of the new tubeless cartridge and infusion set is planned for the first half of 2027, exclusively through pharmacy channels.
The Numbers Behind the Move
TNDM rose 14.6% on Friday, November 13, to $20.07 on volume more than double its three-month average. The catalyst was not the clearance alone. Tandem’s Q3 2026 earnings release on November 5 showed revenue of $283.69 million, up 13.8% year over year, with a diluted EPS of negative $0.10 and gross margin of 57%, up 2.7 percentage points from the prior year. The EPS result beat consensus by $0.14, and revenue beat by $17.84 million.
Pump shipments rose 12% and gross margin improved nearly three percentage points to 57%. Tandem reiterated its 2026 revenue outlook of $1.065 billion to $1.085 billion. International revenue climbed 26% to $93 million. Adjusted EBITDA reached $18.0 million, compared with $2.8 million a year earlier.
The operating losses are compressing fast. That is not a cyclical tailwind; it reflects deliberate business model changes, including the shift toward pharmacy distribution, which carries better unit economics than the traditional durable medical equipment channel.
The Competitive Picture
Tubeless delivery has belonged almost entirely to Insulet. Industry estimates have put Insulet at roughly 58% share of the tubeless insulin pump market, supported by Omnipod’s AID capability, reimbursement reach, and direct-to-patient distribution. Tandem’s tubed pumps have competed on algorithm quality, with Control-IQ+ consistently drawing strong clinical outcomes data, but the form factor gap has been real.
The Mobi’s seven-day wear window closes that gap and arguably inverts it. The system uses continuous glucose monitor sensor values to predict glucose levels 30 minutes ahead and automatically adjust insulin delivery. That is the same Control-IQ+ logic, now available without a tube. Patients who wanted the algorithm but not the tubing no longer have to choose.
Pharmacy coverage for Mobi customers was available for approximately 50% of insured U.S. patients at launch, a figure the company expects to widen through 2027.
Risks Worth Watching
A slower-than-expected shift to pharmacy distribution could weigh on revenue growth next year. The pharmacy channel unlocks better margins, but execution risk is real when you are retraining a salesforce and renegotiating reimbursement agreements simultaneously.
Tandem is also entering a CEO transition. Jeannette Bankes is slated to become CEO effective November 16, 2026, succeeding retiring CEO John Sheridan at year-end. Leadership changes at inflection points introduce uncertainty, however well-telegraphed. The stock’s 52-week range of $12.26 to $29.65 reflects how volatile sentiment around this company can be.
The Gap That Remains
On November 13, TNDM shares rose 14.6% to $20.07, situated within a 52-week range of $12.26 to $29.65. Wall Street’s consensus target sits at $27.18, implying roughly 35% upside from Friday’s close. That gap exists because the market has been pricing Tandem as a tubed-pump company facing structural disadvantage. The FDA clearance disrupts that framing directly.
Two strong quarters, a narrowing operating loss, an international business growing at 26%, and now a tubeless product headed to pharmacy shelves in the first half of next year. Whether TNDM can sustain momentum toward that analyst consensus is worth watching closely over the next two to three quarters.
 Rising Star Stocks