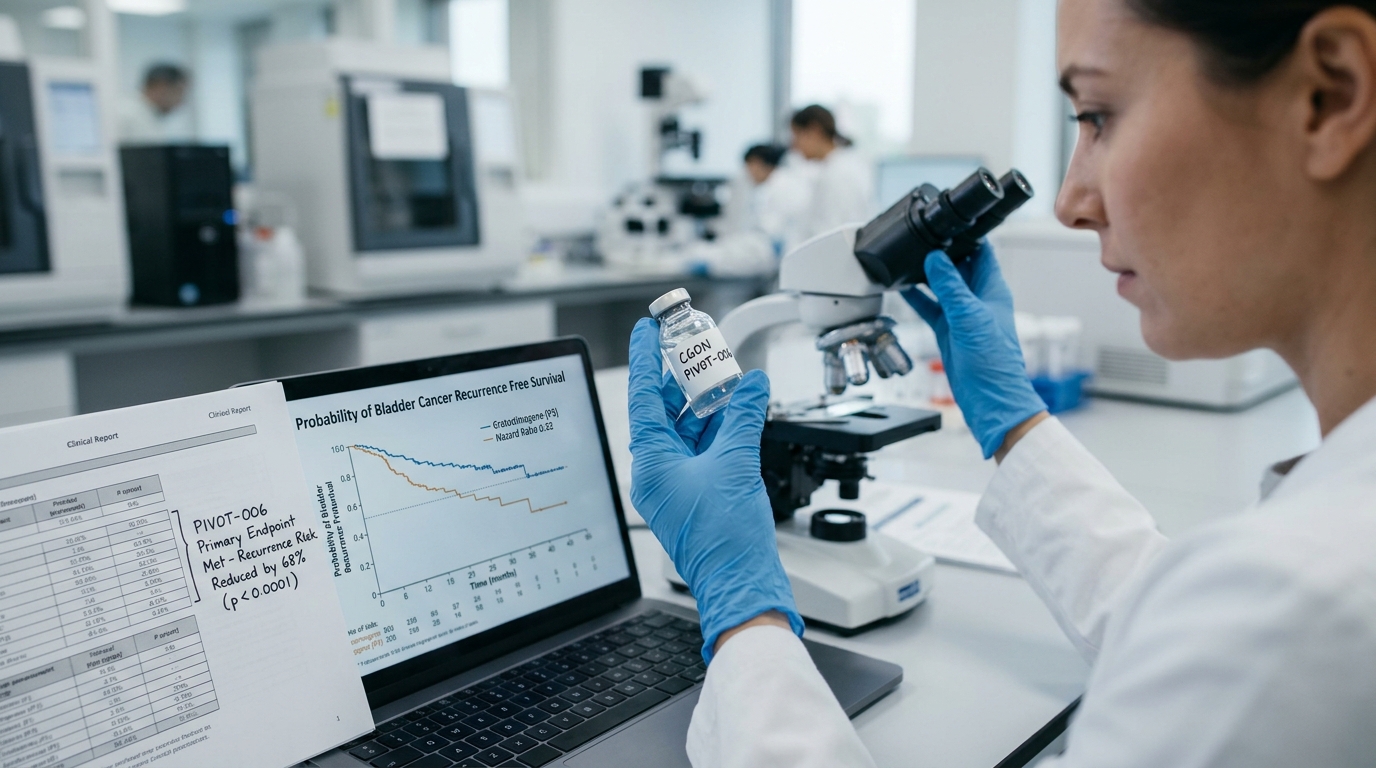
Sunday brought one of the cleanest late-stage readouts in recent biotech memory. CG Oncology’s Phase 3 PIVOT-006 registrational trial of cretostimogene met its primary endpoint, cutting the risk of bladder cancer recurrence by 68% versus the control arm, with a hazard ratio of 0.32 and a p-value under 0.0001. Over a median follow-up of 17 months, there were no Grade 3 or greater treatment-related adverse events and no treatment-related discontinuations. That is about as clean as a registrational dataset gets.
The market agreed, briefly. CGON shares rose nearly 14% on November 16 to a record closing price of $84.78. The stock reached an all-time intraday high of $93.95 that same day, against an all-time low of $14.80 set back in June 2025. By the following session the stock had pulled back sharply, closing at $78.94 on November 17 on volume of about 3.16 million shares.
That reversal matters for anyone considering whether this is a buy today rather than a congratulations for holders.
The Business
Cretostimogene is an oncolytic immunotherapy delivered directly into the bladder. The intermediate-risk and high-grade Ta non-muscle-invasive bladder cancer population it targets includes approximately 50,000 patients and currently has no U.S. FDA-approved adjuvant treatment options. That is an unusually clean commercial opening: a sizable population, an unmet need, and now a Phase 3 dataset supporting a second regulatory filing.
A second BLA submission is planned for Q2 2027. The company is also completing its first BLA for BCG-unresponsive high-risk disease, with the remaining chemistry, manufacturing, and controls module progressing as planned and completion of the BLA submission targeted for Q4 2026.
Why Wall Street Is Paying Attention
The PIVOT-006 result landed a day after Summit Therapeutics said the FDA issued a complete response letter for its ivonescimab BLA in EGFR-mutated non-small cell lung cancer, citing a lack of substantial evidence of effectiveness in the absence of a statistically significant overall survival benefit in the pivotal Phase 3 HARMONi trial. Two oncology companies, two opposite outcomes in 48 hours. The contrast sharpened attention on CGON.
Analyst responses to the PIVOT-006 data were largely constructive. HC Wainwright lifted its price target from $100 to $115 and maintained a buy rating. Wedbush raised its target from $84 to $91 with a buy rating. The broader analyst consensus, though, is more bullish than “moderate buy” and the average target is higher than $96.11 based on widely tracked aggregations.
What’s Driving the Opportunity
The PIVOT-006 topline results will be formally presented at the Society of Urologic Oncology Annual Meeting on December 2, 2026, which gives the stock a near-term catalyst for continued institutional attention. The data package supporting the second BLA appears solid, and recurrence-free survival benefits were observed across both high-grade and low-grade patient subgroups.
What Could Go Wrong
The competitive landscape is not forgiving. Currently approved options in the bladder cancer space include Merck’s Keytruda and Johnson and Johnson’s Balversa, while J&J’s TAR-200 has also reported 12-month landmark data. J&J initiated an NDA submission for TAR-200 in BCG-unresponsive high-risk non-muscle-invasive bladder cancer in January 2025, meaning CG Oncology faces a well-resourced rival moving toward the same patient population.
Then there is the single-asset risk that any honest assessment of CGON must confront. The company’s entire valuation rests on cretostimogene. A manufacturing setback, an FDA complete response letter, or an unexpected safety signal in broader use could reset the stock dramatically. Institutional ownership stands at about 26.56%, which is low for a company with roughly a $7 billion market capitalization and suggests the shareholder base skews toward retail momentum buyers who can exit quickly.
The Bottom Line
The science here is genuinely impressive. A 68% reduction in recurrence with no serious treatment-related adverse events is the kind of result that earns regulatory filings, analyst upgrades, and a 14% single-session gain. The question is whether buying at current prices, after that move and with the stock already pulling back, offers a risk-adjusted return that beats alternatives available today. With two BLA submissions converging, a December conference presentation, and a large unmet-need market, the catalyst path is real. So is the binary exposure of a company with one drug, two pending regulatory decisions, and a heavyweight competitor in J&J. Conviction here requires tolerance for that concentration risk, not just admiration for the data.
 Rising Star Stocks