On March 20, Ross Givens recommended a little-known “SpaceX stock”…
A stock that allows you to profit from SpaceX’s moves…
Even though the company itself is still private.
Less than 2 months after Ross recommended that stock…
It shot up over 180%…
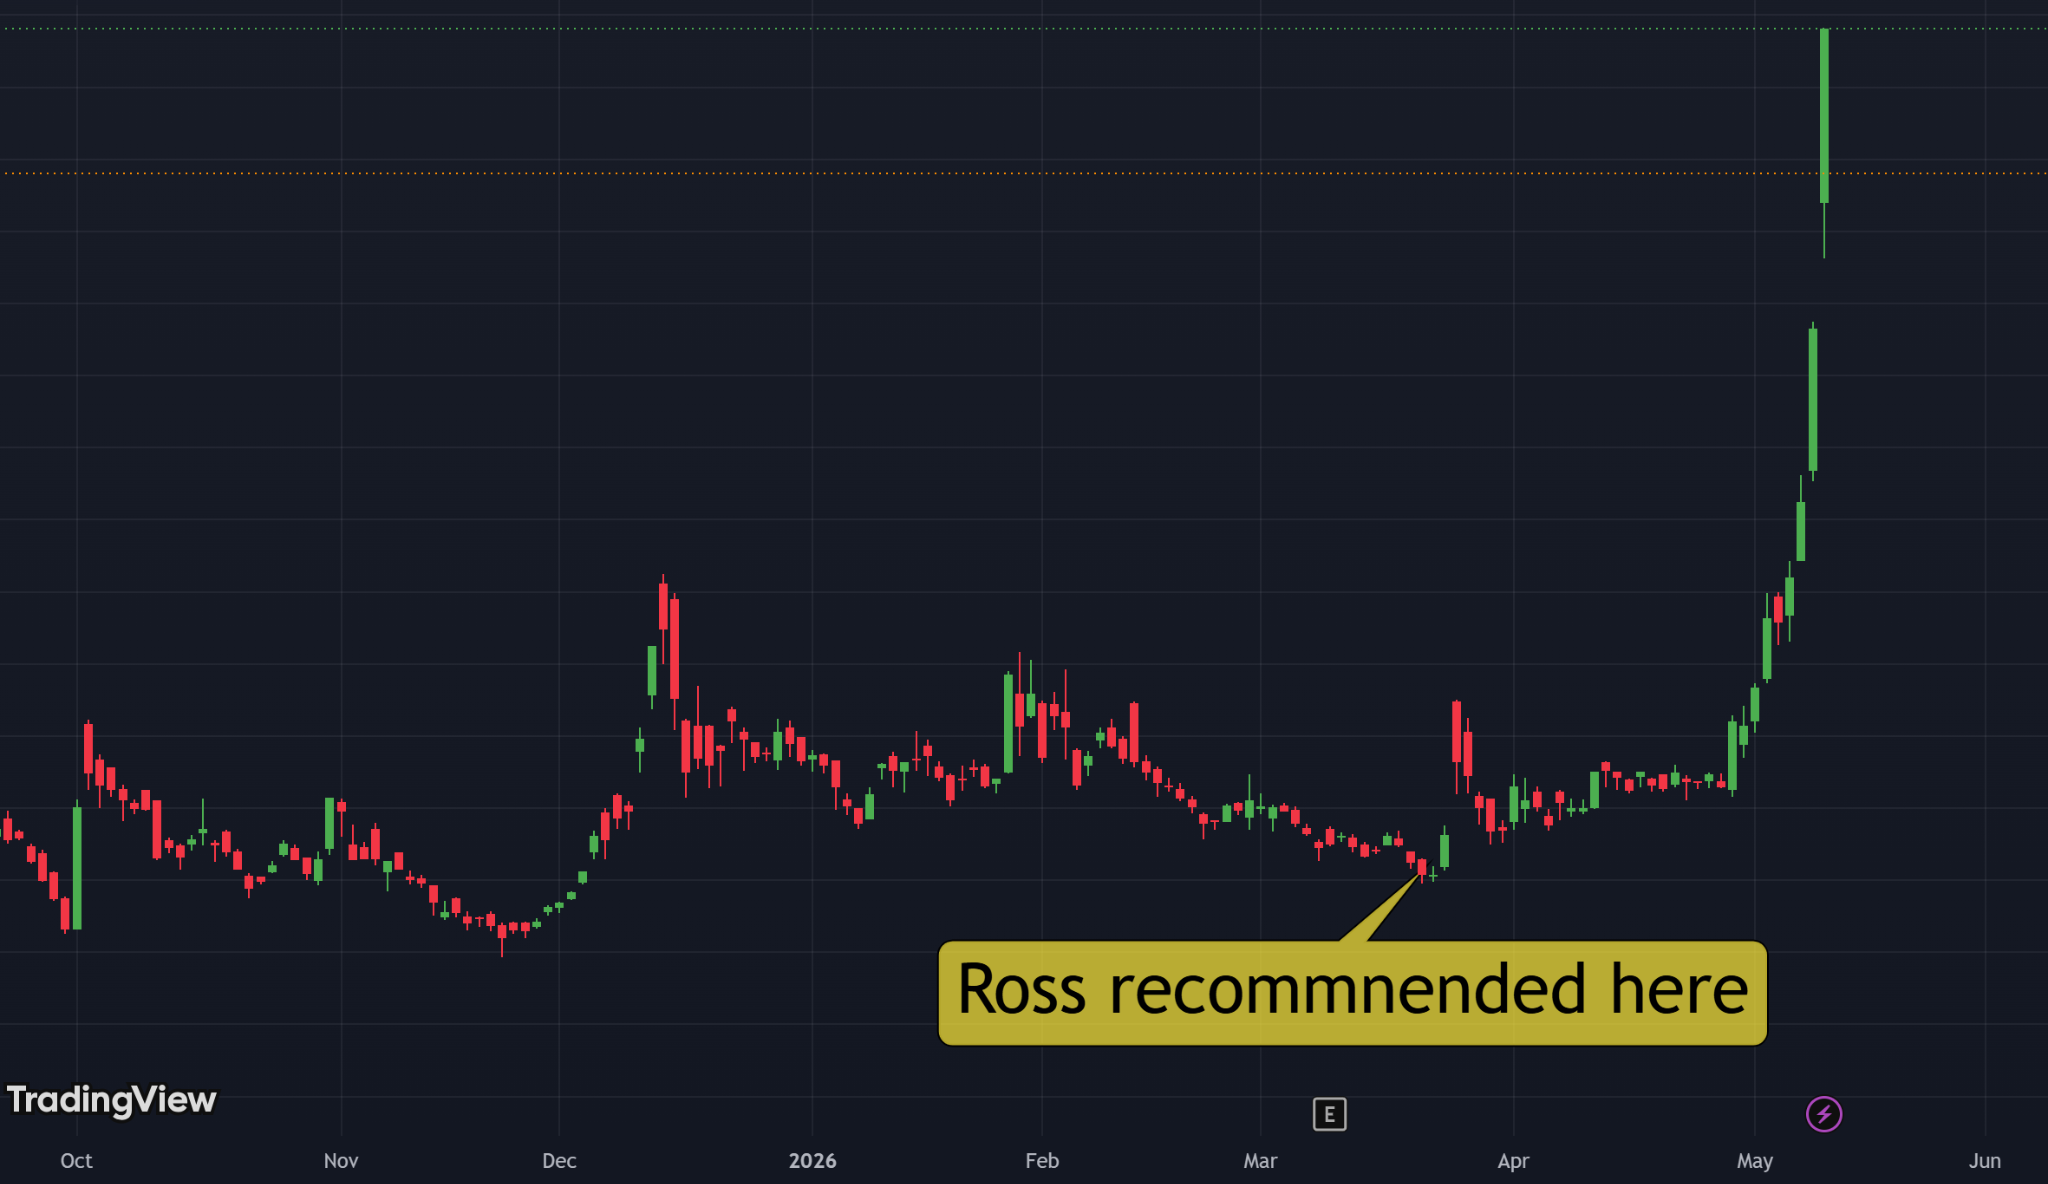
Enough to turn a $5,000 position into over $14,000.
And that’s not the only SpaceX-related stock Ross has recommended.
If you want to get stock recommendations like these…
Then you need to join Ross’ Black Ops Trading Club ASAP…
While the entry price is still $5.
That’s right – $5 to get stocks that could potentially hand you thousands in profits…
On top of LIVE market analysis twice a week.
For $5 you no longer need to navigate this market blindly…
But you can do so with a 20-year market veteran by your side.
We’re not sure how much longer we can keep the price at $5…
So click here to claim your $5 Black Ops Trading Club spot while you still can.
Coherent Just Grew 50%. Now It May Be the Only Big Optics Supplier Left Standing.
Three days ago, Marvell announced it would acquire Lumentum in an all-stock deal valued at roughly $115 billion. The optics industry absorbed the news quietly. Then, on the evening of November 4, Coherent Corp. reported its fiscal first-quarter results, and the implications became impossible to ignore.
The Quarter Itself
Coherent posted revenue of $2.37 billion, up 50% year over year. GAAP gross margin expanded 254 basis points year over year to 39.1%. Shares rose in post-market trading.
These are not incremental numbers. The data center and communications segment now accounts for about 82% of total revenue, up from a business that was meaningfully more diversified just two years ago.
What Changed This Week
Marvell and Lumentum announced their combination on November 2. The transaction carries an implied enterprise value of roughly $115 billion, with Lumentum shareholders receiving 4.5 Marvell shares per share. The deal is expected to close in the first half of calendar 2028.
Until it does, Lumentum remains a separate company. After it does, Lumentum’s photonics capabilities belong to Marvell’s integrated silicon-and-optics platform. That is a fundamental shift in the competitive landscape. Hyperscalers buying optical components at scale now have one fewer independent supplier to call.
The shrinking pool of independent optical vendors sharpens the stakes for every name still standing. Ciena’s position as one of the few publicly traded optical networking vendors with AI infrastructure incumbency shows how quickly that independence can translate into pricing power.
Coherent just became one of the last major independent optics companies in the AI infrastructure stack.
The PhotonLink Signal
During the Q1 earnings call, Coherent discussed PhotonLink as its integrated optics platform for AI infrastructure, and previously said it has multiple customer engagements and long-term agreements in progress. It has also disclosed a multiyear strategic agreement with Nvidia related to next-generation AI optical technologies, including a multibillion-dollar purchase commitment and Nvidia’s $2 billion investment in Coherent.
PhotonLink is Coherent’s integrated optics platform, designed to address the transition from copper to optical connectivity inside AI data centers. The company has described the platform as spanning architectures including CPO, NPO, and emerging chip-to-chip optical connectivity.
The company has highlighted scale across and data center interconnect as growth drivers inside Datacenter & Communications, but it has not publicly substantiated the specific Q1 “scale-across revenue exceeded $200 million, up 53% sequentially and roughly fourfold year over year” figure in a filing or release.
Where the Company Is Pointing
Coherent has previously guided to reaching quarterly revenue above $3 billion by the end of fiscal 2027. The company has also spoken about long-term margin expansion, but the specific Q2 fiscal 2027 revenue range and the claim that full-year pro forma revenue growth is expected to exceed 60% were not verifiable from public filings or company materials available as of November 5, 2026.
Similarly, the specific leverage figure and the claim of negative $868 million of free cash flow in the quarter were not supportable from the quarter’s public filing excerpts available as of November 5, 2026. In its quarterly filing, Coherent reported that operating cash flow was negative in the quarter, reflecting working-capital needs tied to growth.
The Risks Worth Watching
Heavy capital expenditure is the obvious pressure point. Negative cash generation at this scale requires the revenue ramp to arrive on schedule. Any delay in hyperscaler spending or a shift in AI infrastructure architecture could leave Coherent carrying expanded capacity ahead of demand. Concentration risk is also present: with roughly 82% of revenue in a single segment, macro softness in data center buildouts flows directly to the top line.
Final Thought
The Marvell-Lumentum deal reshaped the optics sector in a matter of days. Coherent did not plan this week’s consolidation, but its Q1 results confirm it was already building toward the moment when scale and independence would matter most. A newly concentrated competitive landscape, a revenue trajectory pointing toward $3 billion per quarter, and an improving margin profile make this a company worth tracking closely as the industry reorganizes around it.
 Rising Star Stocks