The bond market has been sending a message for weeks. This morning, Freddie Mac’s weekly Primary Mortgage Market Survey makes that message impossible to ignore on Main Street.
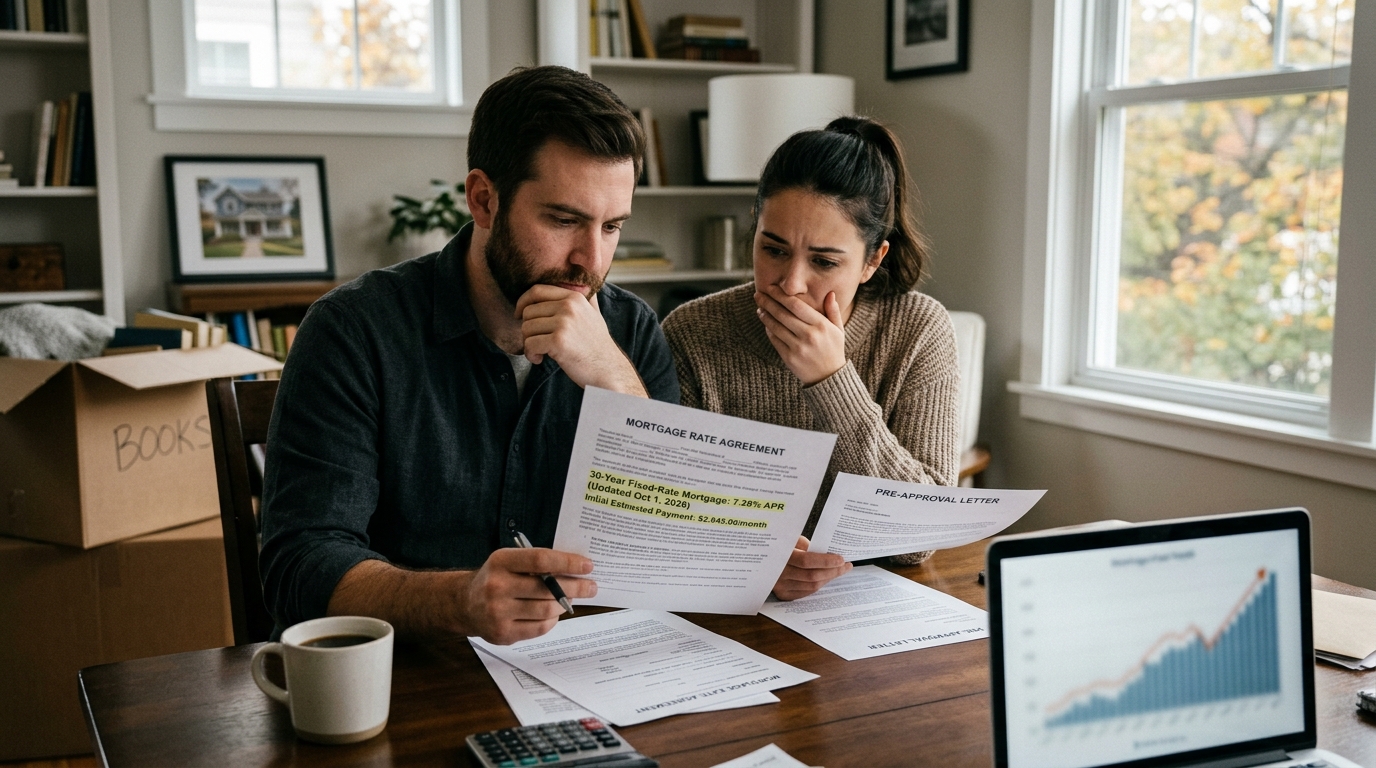
The 30-year fixed-rate mortgage averaged 7.28% as of October 1, 2026, up from 7.03% the prior week. That 25-basis-point single-week jump was the sharpest in four years. But the October 1 figure already looks stale. On October 7, the 10-year Treasury yield climbed to about 5.36%, its highest level since 2002, and that bond selloff helped push the Mortgage Bankers Association’s average 30-year conforming contract rate from 7.30% to 7.49%. Today’s Freddie Mac survey captures the full weight of that week.
This is the clearest example of what market participants mean when they say higher Treasury yields transmit into the real economy. Freddie Mac’s rate is not a market rate in real time. It is a lagged, smoothed confirmation that the 10-year’s move has fully arrived at the closing table.
Realtor.com senior economist Hannah Jones put it directly: the 30-year mortgage rate has risen nearly a full percentage point over the past year, dramatically affecting buyer budgets, adding more than $200 to the monthly principal and interest payment on a median-priced home.
The application data confirms buyers are responding. Mortgage applications decreased 4.2% from one week earlier for the week ending October 2, 2026. With rates roughly a percentage point higher than a year ago, refinance applications fell again and were at their lowest level since January 2025. FHA purchase applications fell the most, declining 6%, as higher rates add to ongoing affordability challenges for many homebuyers. First-time buyers, leaning hardest on FHA financing, are being squeezed out fastest.
The homebuilder stocks reflect that pressure. Truist maintained Hold ratings on D.R. Horton and Lennar while warning that higher mortgage rates will weigh on the sector, particularly lower-end builders. If rates stabilize at current levels through year-end, the spring selling season will begin with rates approximately 140 basis points higher year-over-year. That is the real risk embedded in today’s Freddie Mac reading: not what it says about October, but what it implies about April.
NVR and PulteGroup, which skew toward move-up and higher-income buyers, carry somewhat more insulation. PHM’s buyers generally bring larger down payments and more home equity from a prior sale, reducing sensitivity to monthly payment shock. DHI, with its entry-level Express Homes brand, sits at the other end of that spectrum. D.R. Horton is entering its October 29 earnings date with the housing backdrop still pressured by high mortgage rates and soft affordability.
The five forces driving the 10-year higher are not fading. The Federal Open Market Committee raised its benchmark rate to 3.75%-4.00% in September and projected further tightening, while a projected $1.9 trillion federal deficit and heavy AI-related corporate borrowing have collided with weak auction demand. Global bond selloffs in Japan, Britain, and France have also pulled U.S. yields higher. None of those forces reverse quickly.
What to watch: today’s Freddie Mac number sets the baseline. The MBA’s next weekly rate reading arrives October 14 and will capture whether yields above 5.30% push applications down further. D.R. Horton earnings on October 29 will be the first major builder to report under these conditions, and its guidance on order cancellations and incentive costs will tell the market far more about the housing outlook than any survey.
 Rising Star Stocks