Hi Friend,
Just wanted to let you know you can now get a free copy of my new strategy guide here:
How to Master the Retirement Trade [PDF]

What’s the Retirement Trade?
It’s a simple trading opportunity that appears almost every trading day, between 9:30 and 10:45 am EST where traders are making between $300-$1,100+ per contract.
One of my favorite parts about this trade is how predictable it is. It occurs about 3-5 times each week. And once you know what you’re looking for, and how to enter/exit the trade, this could become another nice stream of income for you.
I’m not sure how long I’ll leave this guide up for. So do yourself a favor and take 5 seconds to download it now. At least you’ll have a copy stored for future use!
>> Click Here to Download Your FREE Strategy Guide Now.
To your success,
Dave Aquino
Partner, Head of Options Trading
Base Camp Trading
IMPORTANT NOTICE! No representation is being made that the use of this strategy or any system or trading methodology will generate profits. Past performance is not necessarily indicative of future results. There is substantial risk of loss associated with trading securities and options on equities. Only risk capital should be used to trade. Trading securities is not suitable for everyone. Disclaimer: Futures, Options, and Currency trading all have large potential rewards, but they also have large potential risk. You must be aware of the risks and be willing to accept them in order to invest in these markets. Don’t trade with money you can’t afford to lose. This website is neither a solicitation nor an offer to Buy/Sell futures, options, or currencies. No representation is being made that any account will or is likely to achieve profits or losses similar to those discussed on this web site. The past performance of any trading system or methodology is not necessarily indicative of future results.
CFTC RULE 4.41 – HYPOTHETICAL OR SIMULATED PERFORMANCE RESULTS HAVE CERTAIN LIMITATIONS. UNLIKE AN ACTUAL PERFORMANCE RECORD, SIMULATED RESULTS DO NOT REPRESENT ACTUAL TRADING. ALSO, SINCE THE TRADES HAVE NOT BEEN EXECUTED, THE RESULTS MAY HAVE UNDER-OR-OVER COMPENSATED FOR THE IMPACT, IF ANY, OF CERTAIN MARKET FACTORS, SUCH AS LACK OF LIQUIDITY. SIMULATED TRADING PROGRAMS IN GENERAL ARE ALSO SUBJECT TO THE FACT THAT THEY ARE DESIGNED WITH THE BENEFIT OF HINDSIGHT. NO REPRESENTATION IS BEING MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFIT OR LOSSES SIMILAR TO THOSE SHOWN.
One Customer Decision Just Re-rated Haemonetics by 16%
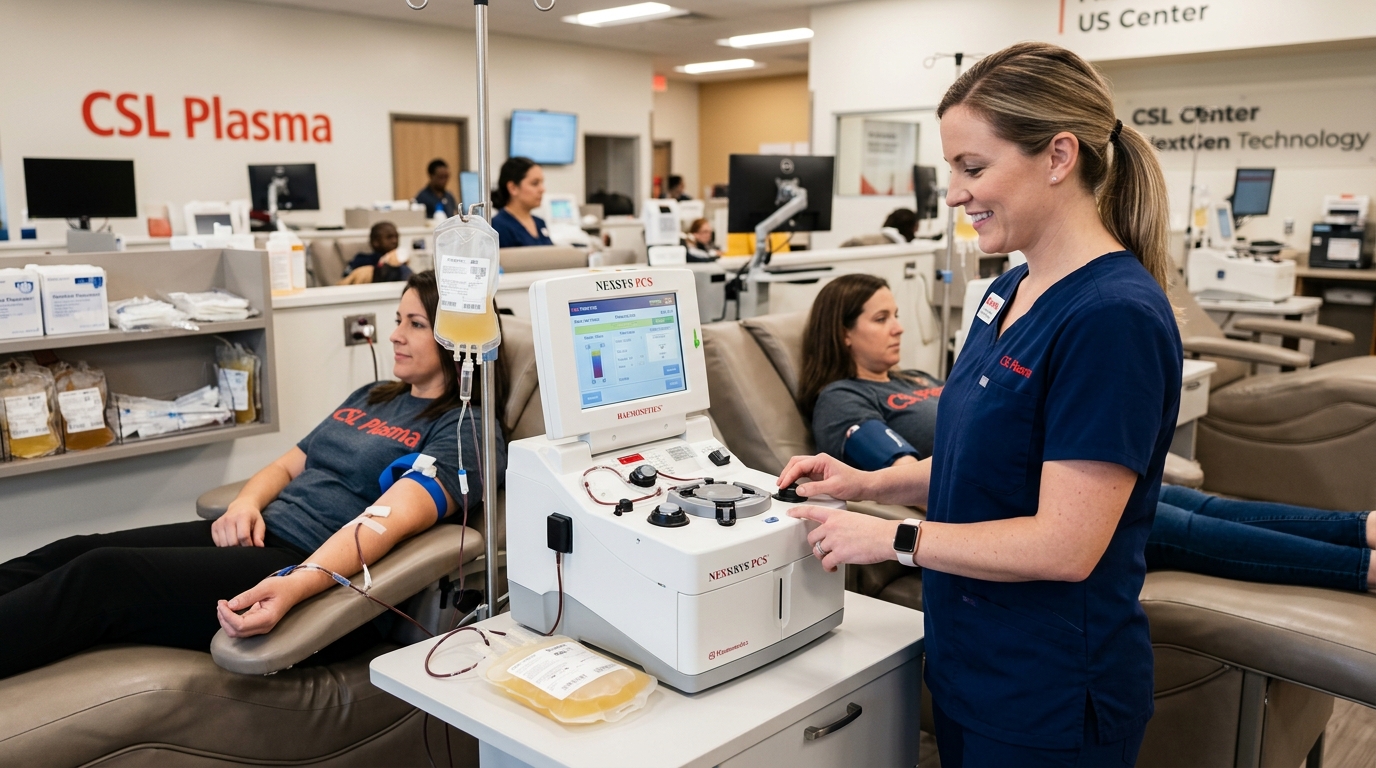
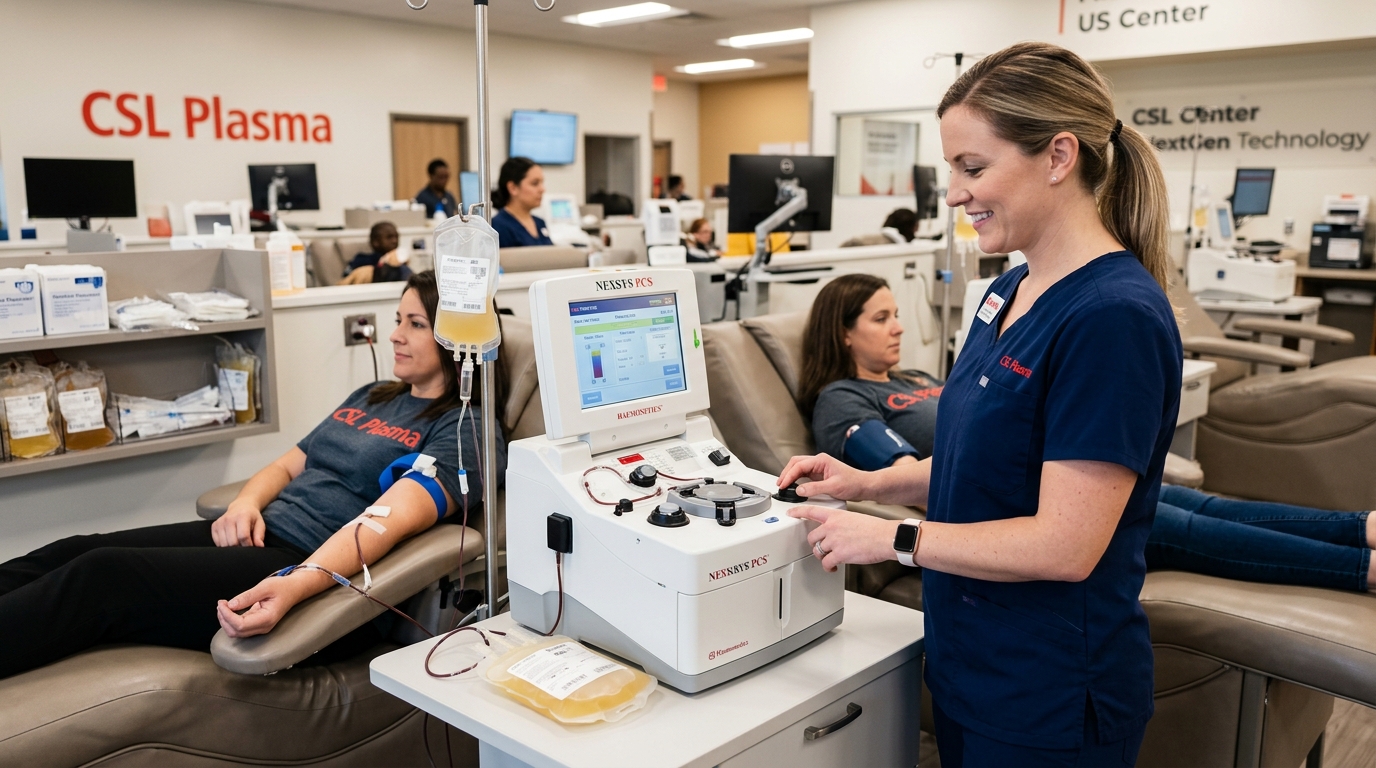
The deal was already two months old. Nobody moved on it in August. Then Thursday morning, a single 8-K filing changed the math entirely, and Haemonetics shares closed about 16% higher on the day.
What Actually Changed
When Haemonetics first disclosed its supply agreement with CSL Plasma on August 18, the language was cautious. CSL may utilize NexSys PCS devices and purchase related disposables. The scope and timing were undecided. Haemonetics did not update its fiscal 2027 guidance. Wall Street noted the deal and mostly moved on.
October 8 was different. CSL told Haemonetics it now expects the transition to occur at all of its current U.S. plasma collection centers, with the full rollout targeted by the end of calendar 2027. That is 300-plus facilities. “Partial” became “complete.” Ambiguous became scheduled. The stock responded accordingly.
Why Disposables Are the Real Prize
Haemonetics does not simply sell machines. It sells the consumable kits used in every collection procedure, and those kits replenish on a per-donation basis. A plasma center that runs hundreds of donors per day is a recurring revenue engine, not a one-time equipment sale. Across 300-plus CSL centers, that disposable stream could be substantial.
Analysts had already framed the revenue potential. Before Thursday’s update, Needham & Co. projected that a full CSL transition could eventually add between $183 million and $223 million in annual revenue to Haemonetics, assuming a pricing premium for the NexSys platform’s newer Persona PLUS technology. Persona PLUS, which received FDA clearance in February 2026, delivers on average a mid-single-digit percentage increase in plasma yield per donation over Persona. That yield improvement is the commercial argument CSL is evidently buying.
The Context That Makes the Move Make Sense
This is not a new customer. It is a returning one, and the gap years matter. CSL’s contract with Haemonetics expired in mid-2022 and was not renewed. In the interim, CSL equipped its entire U.S. network with Terumo’s Rika systems, with CSL and Terumo announcing the nationwide U.S. rollout was completed in September 2025.
Now the trajectory reverses. Haemonetics posted Q1 fiscal 2027 revenue of $339.4 million, up 5.6% year-over-year and ahead of consensus estimates that clustered around the high-$320 millions to roughly $329 million depending on the source. North American plasma disposable volumes were already running up in the mid-20% range organically in the most recent quarter. CSL’s return layering onto that base is what Wall Street is repricing.
Analyst Reaction
BTIG raised its price target from $110 to $130, lifting its valuation multiple to approximately 21 times forward earnings from 18.5 times. The firm said it is not yet embedding any CSL revenue into its model, pending detail on the rollout cadence. That is a meaningful disclosure: the target move is primarily a multiple re-rating, not a revenue upgrade. If CSL delivers, the earnings revisions come separately, on the November 5 earnings call.
Citi had already upgraded HAE to Buy in September, lifting its target from $92 to $123, and estimated that each 10% recovery of CSL business could add roughly $0.13 to annual earnings per share.
Risks Worth Noting
The agreement is non-exclusive and carries no minimum purchase commitments. CSL can still change the scope and timing. Haemonetics itself flagged that implementation details remain to be determined. The stock now trades at a forward multiple above its five-year average of roughly 19 times, meaning there is less room for disappointment than there was a week ago. A slower-than-expected rollout or any renegotiation of scope could unwind a portion of Thursday’s gains quickly.
The Bigger Picture
What Thursday confirmed is that Haemonetics’ NexSys platform, particularly with Persona PLUS, is differentiated enough for the world’s largest plasma company to switch suppliers twice. CSL left, ran Terumo’s system for several years, and is coming back. That is a meaningful product validation. For investors, the disposable revenue model tied to 300-plus high-volume collection centers is the kind of recurring base that commands a durable premium. How fast CSL installs the hardware determines when that premium is earned, not just assumed.
The November earnings call is the first real checkpoint. Management has signaled it will provide a more concrete financial impact estimate then. Until that number arrives, HAE is a company whose largest customer just came home, with the revenue still to be confirmed.
 Rising Star Stocks