October 7, 2026
Bonus Content: Nebius Jumped 9% on an AI Deal. Its COO Sold $117 Million of Stock the Day Before.
My accountant is going to kill me when she sees this.
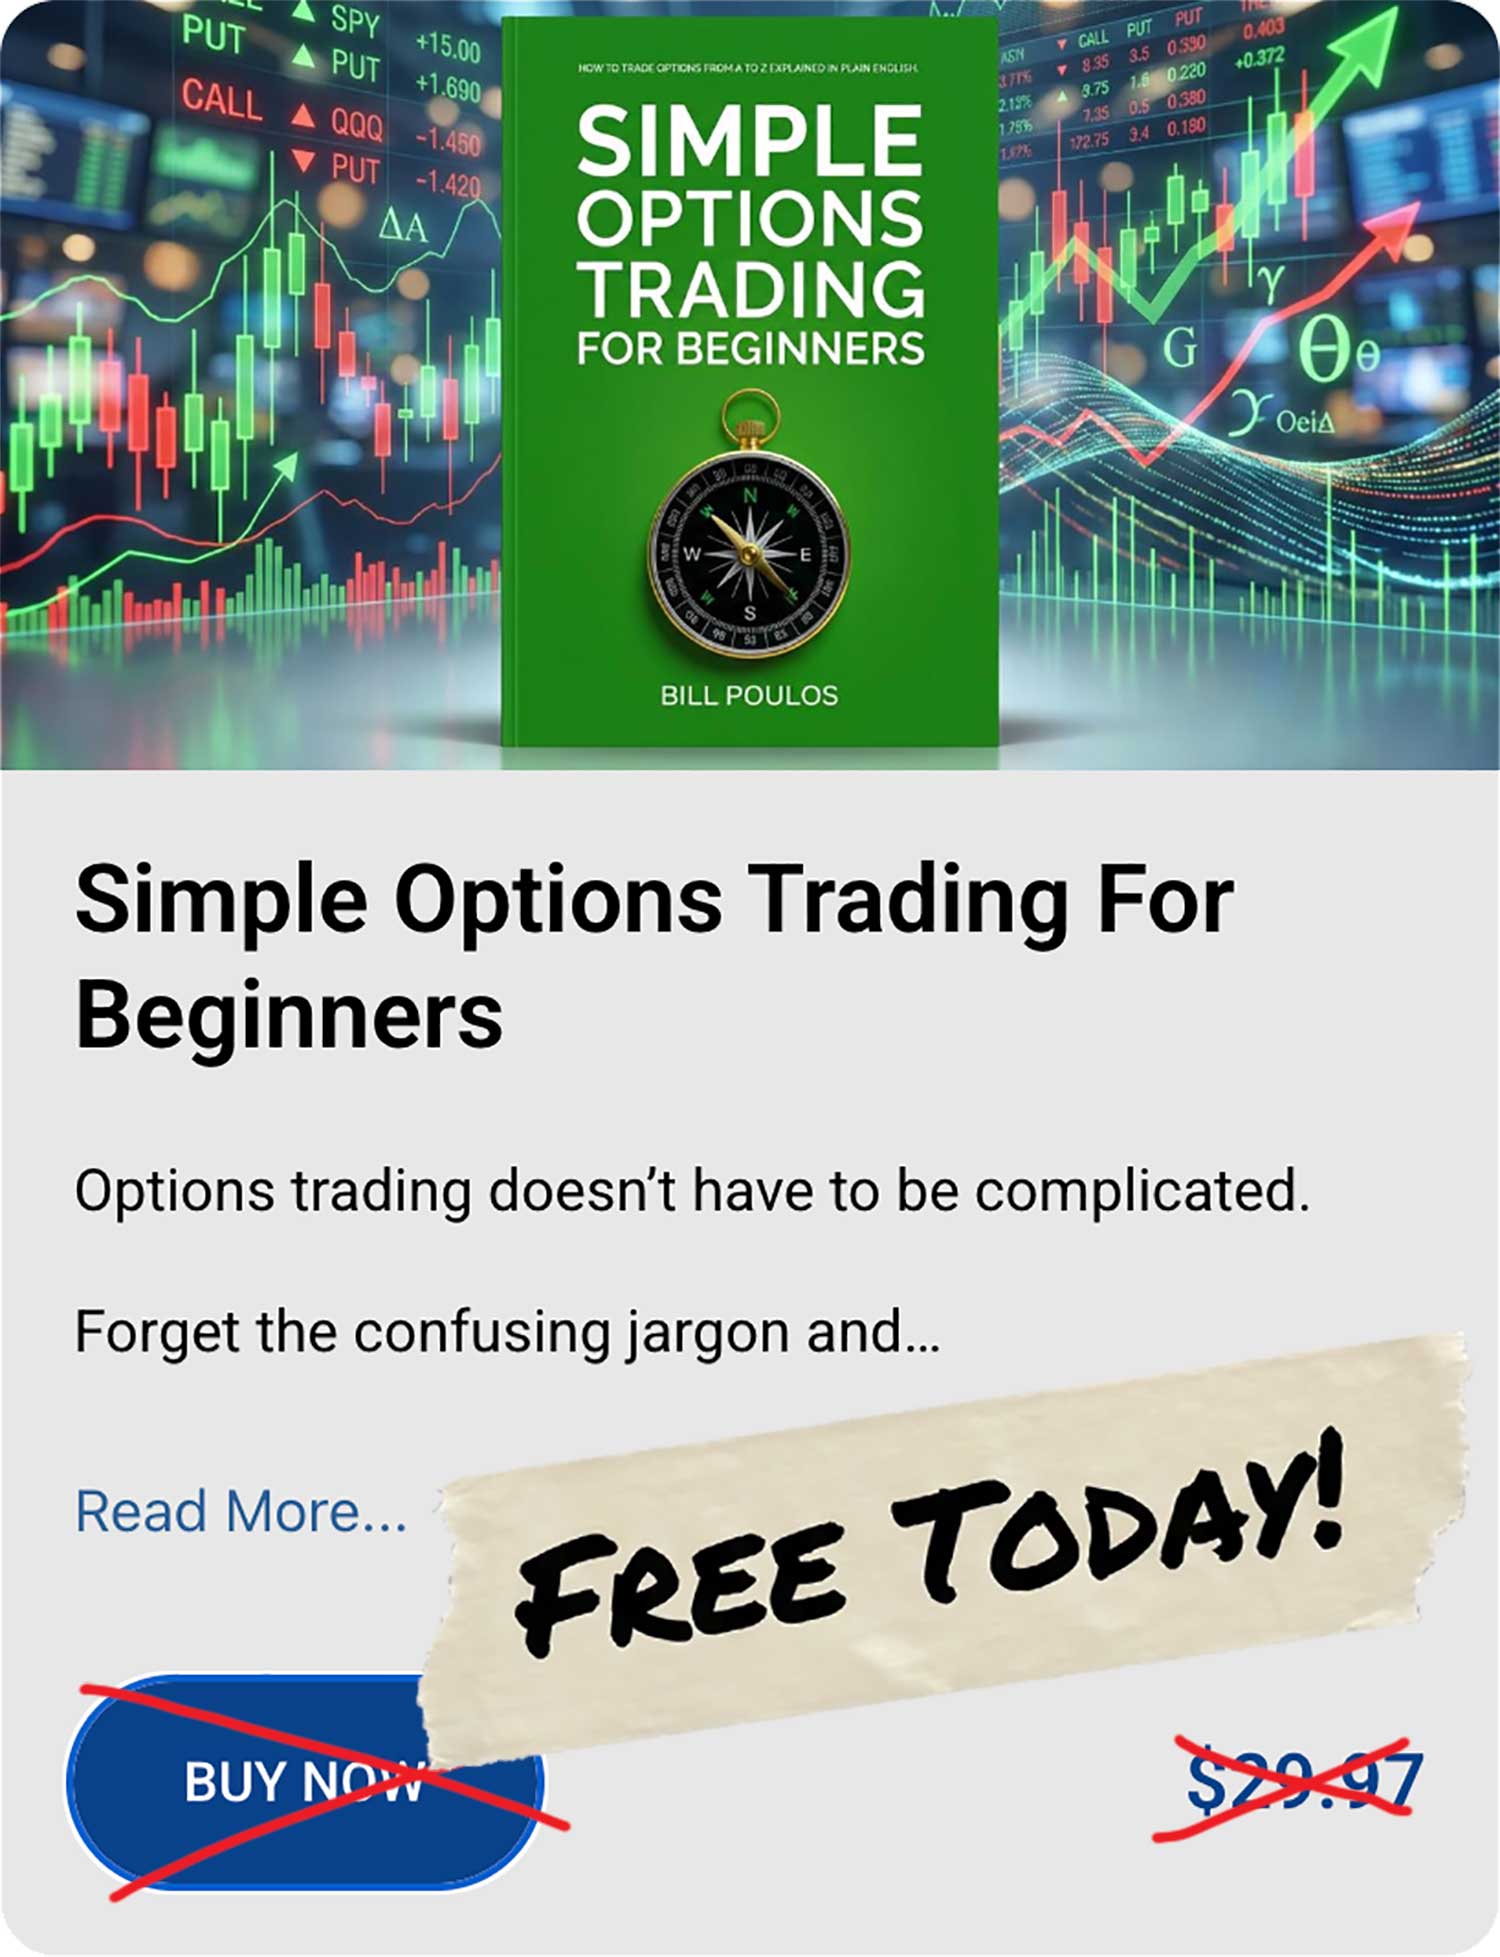
She specifically told me to stop giving away my “Simple Options Trading For Beginners” book for free.
“Bill, you’re leaving money on the table,” she said. “That book sells for $29.97 on your website.”
She’s right. But here’s what she doesn’t understand…
Every trader I help avoid the mistakes I made is one less person who’ll quit trading in frustration like I almost did decades ago.
So against her advice, I’m sending you this email.
Right now, you can grab a copy of the same book selling for $29.97 on our website… completely free.
It reveals the ONE options technique that took me 11 years to discover (and saves you from wasting time on the other 47 strategies that don’t work).
Inside, you’ll find out:
- Why “more strategies” actually means “more losses”
- The 10-minute nightly routine that replaced my 8-hour trading days
- The specific market setup I look for (it’s almost embarrassingly simple)
Click here to get your free copy before my accountant locks me out
Good Trading,
Bill Poulos
P.S. You can buy this book right now for $29.97, or you can grab your free copy here.
Nebius Jumped 9% on an AI Deal. Its COO Sold $117 Million of Stock the Day Before.
Tuesday’s session handed Nebius Group one of the cleaner AI headlines of the year. Shares rose 9% to $254 in afternoon trading following a small artificial intelligence inference deal that came with no disclosed price. CoreWeave added about 4% on the same session, Oracle gained about 3%, while broader AI funds SKYY and QQQ each gained under 1%, keeping the rally concentrated in pure-play AI infrastructure names. That selective lift matters. The market is not rewarding the sector generally. It is picking the companies it believes will own rented AI computing capacity.
What Nebius Actually Bought
On October 1, Nebius announced the acquisition of Inferize, an inference optimization company whose technology and engineering team have been folded into Nebius Token Factory, its managed production AI inference platform. Founded in January 2026, the Inferize team had a working prototype within three months.
The problem they solved is real. Cold starts, the time models need to load before serving a single request, impose additional time and costs on teams running AI models in production at scale, leaving assigned GPUs idle at launch, during demand spikes, and when weights are updated mid-run. Inferize’s technology cuts this “idle GPU tax,” enabling capacity to scale much more closely with actual usage and driving higher capacity utilization and better token economics. For a company that rents GPU time, squeezing idle capacity is a direct margin lever.
The Business Behind the Pop
The underlying financials give the rally something to stand on. Revenue grew 454% year over year to $582 million in Q2 2026, up 46% from the prior quarter. Annualized run-rate revenue reached $3 billion, while group adjusted EBITDA turned positive at $236 million with a 41% margin. A year ago those margins were deeply negative.
Nebius says it has more than $40 billion in contracted revenue from investment-grade customers, including Microsoft and Meta Platforms. For scale, the company’s revenue for all of 2025 was about $529.8 million, meaning Nebius has signed up roughly 75 times its 2025 revenue. That is the number the market is pricing, not the trailing earnings figure.
The Multiple That Stops Conversations
Nebius carries a trailing twelve-month price-to-earnings ratio near 197x, a level that makes the shares hard to own on conventional terms. The price-to-sales ratio of roughly 49x significantly exceeds its historical median of approximately 7x, as well as the industry median. Anyone running a traditional screen will reject this stock on the first pass.
The counter-argument lives in the backlog. Remaining performance obligations grew to around $37.5 billion by June 30. Approximately 70% of Q2 deals carried upfront prepayments, and customer prepayments are expected to provide more than $9 billion of funding in 2026 alone, covering 50% to 60% of the associated capital expenditures. That structure converts future obligations into present cash. It is not a normal software backlog; customers are pre-funding the hardware.
The Insider Signal Worth Noting
Here is where Tuesday’s picture gets complicated. COO Ophir Nave disclosed the sale of 500,000 Class A shares on October 5, executed under a Rule 10b5-1 plan adopted on May 22, 2026, leaving him with 454,685 Class A shares in direct beneficial ownership. The shares were sold at prices ranging from $230.67 to $243.72 per share. At those levels the transaction was worth roughly $118 million.
The shares sold represent settled restricted share units, approximately 17% of the COO’s granted equity in Nebius Group. A pre-scheduled 10b5-1 plan removes the element of surprise, and insiders at high-growth companies routinely diversify. Still, the timing is what observers will catalog. There have been zero insider buys at Nebius over the past year against 32 insider sells.
Risks
Customer concentration is the sharpest edge. Revenue is concentrated, with three unnamed customers making up 24%, 21%, and 14% of second-quarter revenue. Lose one of those, and the model changes materially. Capital intensity is also staggering: management has guided for capital expenditures between $20 billion and $25 billion for the full year 2026. That pace of spending requires the contracted revenue to actually flow. Some of the most optimistic analyst estimates put Nebius revenue around $48.4 billion by 2030, an assumption that requires financing costs and dilution to stay manageable.
The Bigger Picture
Nebius is a useful lens for understanding where AI infrastructure investment is heading. The pure inference layer, not training, not chips, but the runtime economics of actually running models in production, is becoming its own competitive battleground. Acquiring Inferize for undisclosed terms is a small move. What it signals is that Nebius is building the efficiency stack, not just the capacity stack.
At around 197 times trailing earnings and with its COO banking roughly $118 million in stock this week, NBIS is not a comfortable hold. It could also be that the discomfort is the point. The contracts are large, the growth is real, and the inference efficiency angle is genuinely differentiated. Watch whether the idle GPU tax argument translates into improving unit economics over the next two quarters before drawing a firm conclusion.
 Rising Star Stocks