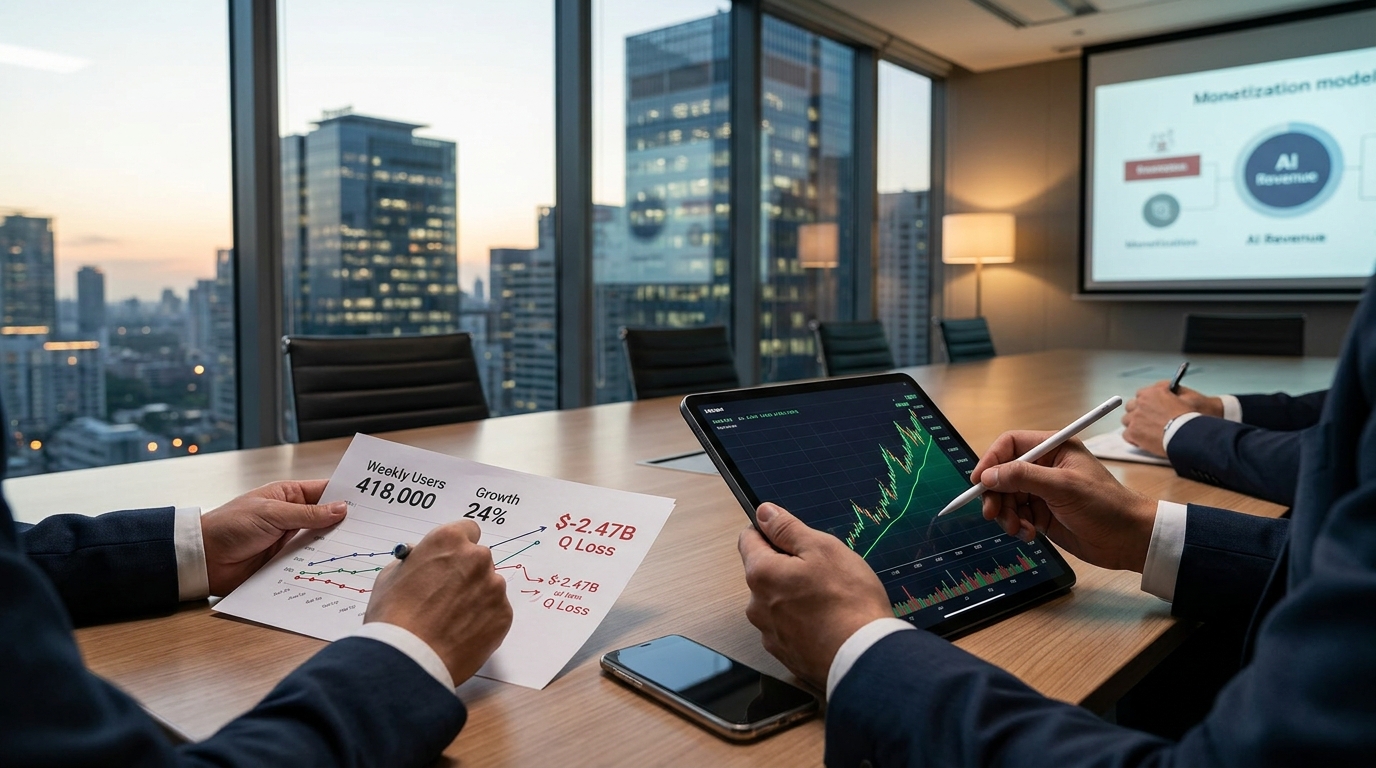
The headline number is 418,000. That is how many weekly users Grok Bot logged as of September 14, according to an internal SpaceXAI presentation delivered in London and reported by Bloomberg. Launched on August 11, 2026, the agent grew 24% in a single week. The growth rate is not the question traders should be asking. The burn rate is.
The Monetization Gap
SpaceXAI’s S-1 disclosed that the AI division lost $2.469 billion in Q1 2026 on $818 million in revenue. The Q2 picture improved: the AI segment generated $2.561 billion in a single quarter, annualizing above $10 billion, per SpaceX’s Q2 2026 earnings release. But the loss column has not closed. Enterprise contracts are explicitly designed to accelerate the path, which is precisely why Grok Bot launched into that lane rather than the consumer market where Meta’s Muse app is playing.
Pricing starts at $120 per seat per month on Cursor Premium Teams, rising to $200 for Cursor Ultra and $300 for SuperGrok Heavy. At 418,000 users and a blended seat assumption of $150 per month, the monthly revenue potential runs roughly $63 million, or about $750 million annualized, assuming full conversion. Those are optimistic assumptions. SpaceXAI has not disclosed what portion of its user base is on paid tiers versus trial access; the enterprise free-trial rollout for existing Grok and Cursor customers adds further noise to any conversion estimate.
For context: Salesforce’s Agentforce reached $800 million in annual recurring revenue by the end of fiscal 2026 and has closed 29,000 deals. Grok Bot is entering a market where the benchmark is already set and the incumbent has a deep CRM moat.
Enterprise vs. Consumer: Two Different Clocks
Meta’s Muse pulled 730,000 US downloads in its first ten days. The consumer distribution is faster, the monetization per user is lower. Grok Bot’s architecture runs the opposite way: each Bot has its own persistent cloud computer, signs into the customer’s existing tools without requiring APIs, and continues executing tasks while the laptop is closed. That is a different sales cycle. Enterprise procurement is slower, but the average contract value is multiples higher than a consumer subscription.
Gartner projects 40% of enterprise applications will include task-specific AI agents by the end of 2026, up from under 5% in 2025. The global agentic AI market is estimated at $19.33 billion this year and is projected to reach $205.88 billion by 2033 at a 40.2% compound annual growth rate. Grok Bot is early inside a large, accelerating addressable market. Whether SpaceXAI can capture enough of that market to materially reduce an AI division burning several billion dollars per quarter is the structurally important question.
SPCX: The Technical Framework
SPCX is trading near $154.05. The stock is down about 32% from its $225.64 intraday high and has since recovered into a consolidation range. Near-term resistance sits at $153 to $154; a sustained close above that level opens the path toward $160 to $165. On the downside, $139 to $140 is the key support floor, with the IPO price of $135 acting as a structural anchor below that. VWAP has drifted up from the August low, and the rising channel from that floor is intact, but the stock has yet to reclaim its 50-day moving average in any sustained way.
The next binary catalyst is Starship Flight 14, scheduled for September 28. Institutional consensus sits at a buy rating, with an average 12-month price target of about $222. Macquarie’s target is $250. The spread between current price and analyst targets is wide, but so is the lock-up schedule: insider tranches continue unlocking through December 2026, adding persistent supply pressure at every rally attempt.
Scenario Modeling
Bull Case ($175 to $185): Grok Bot weekly users sustain 15% to 20% growth through Q4, enterprise conversion rates prove out above 60%, and SpaceXAI discloses AI segment operating loss improvement in the next quarterly report. Starship Flight 14 succeeds and pulls forward commercial revenue estimates. Lock-up sellers absorb into institutional buying.
Base Case ($145 to $158): Grok Bot growth continues but conversion data remains opaque. AI segment losses narrow modestly. SPCX consolidates inside the current range as the market waits for Q3 financials and a cleaner picture of how enterprise seat revenue maps to the income statement.
Bear Case ($125 to $135): Weekly user growth decelerates below 10%, the enterprise free-trial period ends without visible conversion, and AI division losses remain above $2 billion. A rejected breakout at $153 combined with sustained insider selling drives a retest of the $135 IPO level or below.
Active Trader Framework
The 418,000-user figure is compelling enough to shift sentiment, but it is one data point from one internal presentation, not an audited metric. Position sizing should reflect that uncertainty. The $153 to $155 zone is the decision area: watch for volume-confirmed closes above it before extending long exposure. On the short side, a rejection at current levels with expanding volume into the $139 to $140 support is the level where the risk-reward shifts. Volatility is structural given the lock-up calendar and the lack of a full trading history. Risk frameworks must account for moves of 8% to 12% on catalyst days.
Preparation means knowing where the next number comes from. For Grok Bot, that is the next internal milestone SpaceXAI chooses to disclose, or the Q3 earnings call, where AI segment revenue and the word “Grok Bot” should both appear in the same sentence for the first time.
 Rising Star Stocks