As copper breaks records… capital is turning toward early-stage discovery stories that are only beginning to unfold.
One under-the-radar Canadian copper company – still trading undiscovered below $2 per share – is emerging at exactly the right moment.
The company controls a historic copper belt in Canada’s Yukon that produced for decades… and is now being explored as a unified system for the first time.
And the results are starting to speak for themselves:
- High-grade copper confirmed at the flagship
- Past-producing areas getting a fresh look via the drill bit
- Multiple additional targets advancing toward drilling
Multiple rigs are already operating. More are being added. And the company is fully funded through the end of 2027 for its biggest exploration program yet.
More rigs. More drilling. Multiple shots at discovery – from a copper stock still trading below $2.
We’ve compiled a FREE online report detailing the high-grade results, the district-scale opportunity, and where the 2026-27 drill campaign goes next – including our exclusive interview with the company’s CEO.
Click here for instant access – and get the full story before the next round of drill results arrives.
China Tightens Humanoid Robot IPOs. UBTECH Has Orders.
Beijing has a way of cooling a market by making it prove itself. This week it did exactly that to humanoid robotics.
The Gate Just Got Narrower
The China Securities Regulatory Commission issued informal guidance that amounts to a hard filter for the embodied AI IPO wave. Companies must show steady revenue backed by commercial orders, shrinking losses with a three-year forecast, and ownership of core technology such as a robotic brain or functioning hands. The guidance is not a formal rule, and sources told Reuters a company might need to meet only two of the three tests. Even so, the bar stings. Reuters also reported that at least two dozen humanoid-related embodied AI companies have filed to list in Hong Kong alone, and it is now far less clear how many could qualify.
China’s humanoid robotics sector has somewhere between 100 and 150 companies, many existing in a narrow commercial lane of research partnerships, education applications, and pilot projects that have not scaled into repeatable revenue streams. Companies that might have listed in late 2026 or early 2027 will likely need to spend additional quarters building revenue traction before their applications clear review, and for smaller firms burning through venture capital with no clear commercial path, the delay could be existential.
For investors, that is not a dead end. It is a redirect.
The One Name That Already Passes
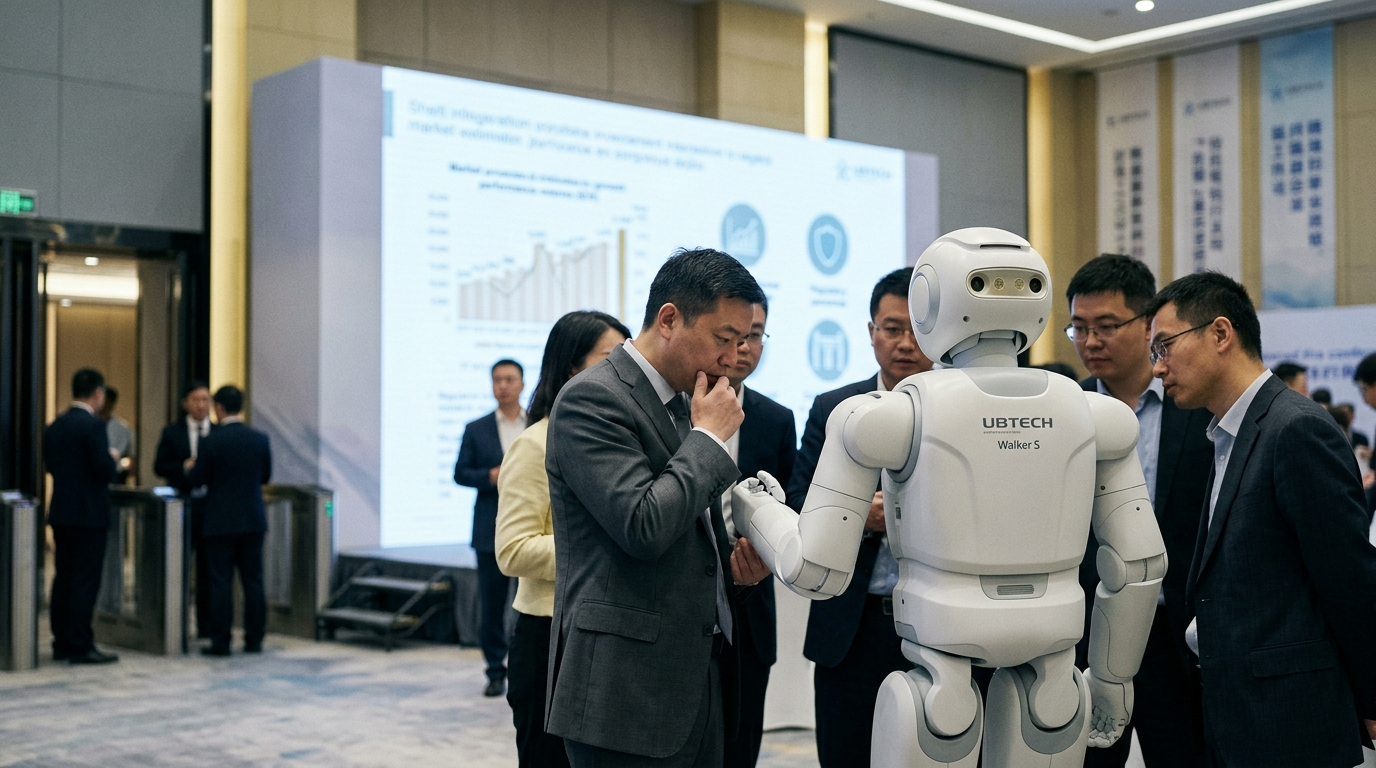
UBTECH Robotics (HKEX: 9880) did not wait for regulators to decide what commercial traction looks like. It built it. Full-size embodied intelligent humanoids became its largest revenue line in 2025, with group revenue reaching RMB 2.001 billion, up 53.3% year over year, and RMB 820.6 million coming from full-size humanoids on 1,079 units delivered.
The acceleration in 2026 is sharper still. First-half results showed group revenue of RMB 1.269 billion, up 104.2%, with full-size humanoid revenue of RMB 590.3 million, up 1,445%, on 921 units delivered. UBTECH remains loss-making, but the interim report showed the scale effect is starting to matter.
Mass production and deliveries began in November 2025 with orders above RMB 800 million, and UBTECH has targeted annual capacity of 5,000 industrial humanoid robots by 2026. It has named customers and partners that include Audi FAW and Foxconn, among others. Those are not just pilot programs. They are disclosed customer relationships tied to an order book and delivered units.
In late June 2026 it launched the Walker C1 for commercial service and the U1 consumer companion series, and the company said cumulative U1 orders surpassed 13,361 units as of the launch event.
Why the IPO Crackdown Helps Rather Than Hurts
The scrutiny follows a surge in funding and listings interest, with Reuters describing regulators’ concern that valuations and some revenue tied to state-backed projects may not reflect durable commercial demand. If the CSRC’s filter drains froth from pre-revenue names, it also pushes institutional attention toward the handful of players with real order books.
The irony is that UBTECH’s stock has not cleanly tracked its operational momentum. H1 2026 revenue doubled to 1.27 billion yuan and humanoid sales jumped 1,445%, yet shares are up, not down, year to date as of late September 2026. On the Street, third-party consensus pages show roughly 11 analysts with an overall “Strong Buy” consensus, and the average published price target implies substantial upside from recent trading levels, though the exact percentage varies by data vendor and day.
Risks Worth Owning
UBTECH remains loss-making. In the United States, the FCC added “foreign-produced advanced robotic devices” to its Covered List on July 28, 2026, which can block new FCC equipment authorizations for covered foreign-produced robot models unless they obtain a Conditional Approval from the U.S. Department of War. Revenue is still heavily concentrated in customized industrial projects rather than a scalable catalog product. And the Walker C1’s commercial deployment is early, not proven at scale.
The Bigger Picture
Chinese manufacturers delivered more than 18,500 humanoid robots in the first half of 2026, representing over 97% of the roughly 19,100 units shipped worldwide, a 272% jump from a year earlier, according to estimates from research firm Smart Analytics Global that were widely reported in August 2026. Beijing is not cooling that industry. It is sorting it, separating companies with order books from those living on press releases. UBTECH may be the clearest example of what passes that test.
 Rising Star Stocks