Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Did you see this?
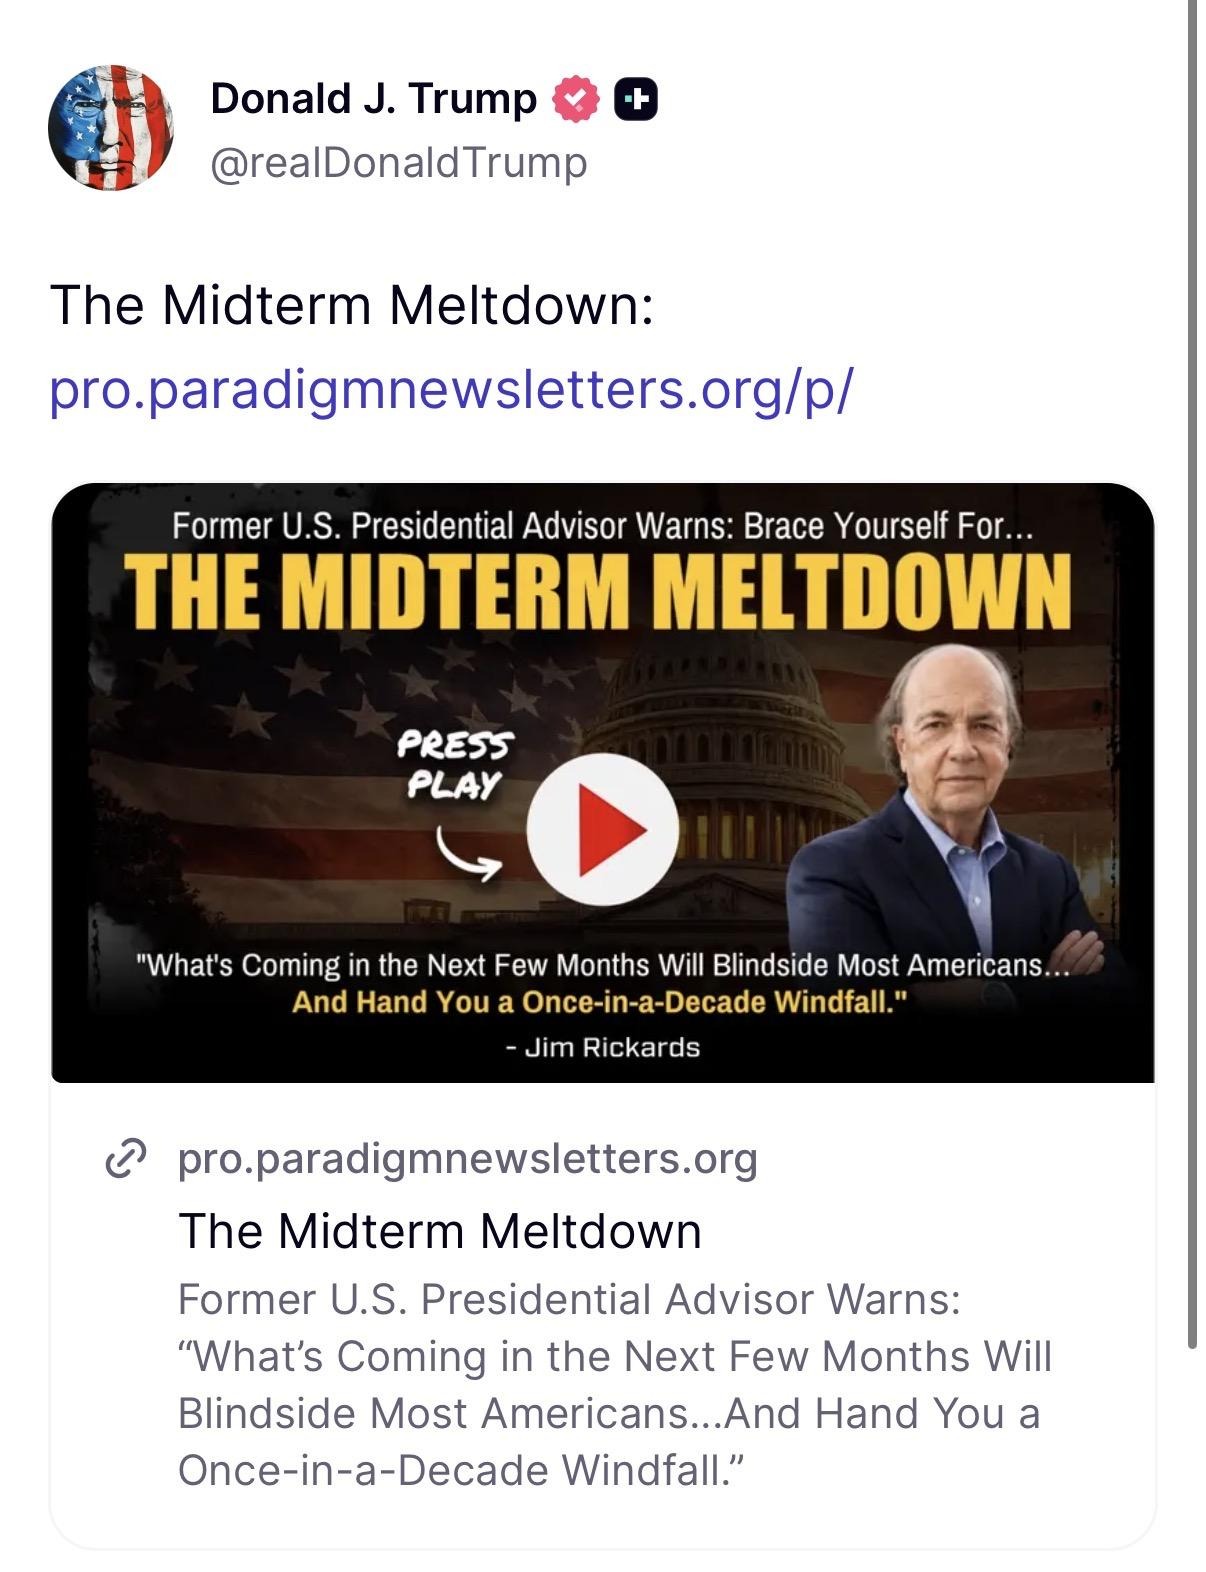
At 12:34 in the morning, the President of the United States shared a video on Truth Social.
Along with just three words:
“The Midterm Meltdown”
By sunrise, the national press had picked it up – and they were not happy about it.
Because if this video proves correct?
They along with the most corrupt politicians in DC could soon be in serious trouble.
I can’t say how much longer this video will be online…
But I can tell you, if its creator is even half right…
This summer could mark the most serious turn in American history since the Civil War.
And for investors who aren’t prepared, it will be a bloodbath.
For the full story, click here.
Regards,
Aaron Gentzler
VP of Research, Paradigm Press
Penguin Solutions Reports Tonight. It’s Still 30% Below Its Peak.
Everybody knows Nvidia. Most people who follow AI infrastructure know Dell and HPE. Penguin Solutions (PENG) is the name they tend to miss, and Tuesday night it closes its fiscal year with a quarter that could force a reckoning with that oversight.
The Numbers on the Table
Seven analysts have settled on $0.77 per share and about $519 million in revenue for fiscal Q4 2026, due after the close on October 6. Those aren’t aggressive targets. The consensus EPS estimate has climbed from $0.64 just ninety days ago, reflecting a steady stream of upward revisions as demand visibility improved. The range runs from $0.73 to $0.80, with revenue projections spanning roughly $507 million to $541 million. The street is not braced for a miss.
Context sharpens the picture. A year ago in Q4, Penguin earned $0.43 per share on $337.9 million in revenue. If consensus holds Tuesday, that works out to roughly 79% EPS growth and about 54% revenue growth year over year. For a company with roughly a $3.1 billion market cap as of October 2, that pace demands attention.
What the Business Actually Does
Penguin describes itself as an AI Factory Platform Company. It designs, builds, and manages next-generation AI data center infrastructure for enterprises, sovereign AI programs, and neocloud providers. The platform combines memory, compute systems, infrastructure software, and end-to-end services. The ambition is to own the full rack rather than just one component.
The key growth engine is Integrated Memory. In Q3 FY2026, reported July 7, that segment surged 111% year over year to $275 million as accelerating AI-driven demand pushed both pricing and volume. The company also became an NVIDIA AI Factory Specialized Partner, a designation that recognizes expertise in deploying full-stack AI factory infrastructure.
The Momentum Behind Tonight
Last quarter was not a fluke. Q3 net sales came in at $478.7 million. Non-GAAP EPS hit $0.84. The company responded by lifting its full-year FY2026 outlook to 22% net sales growth and non-GAAP EPS of approximately $2.60, both above the prior high end of guidance.
Management also noted that customer demand continued to outpace reported revenues entering Q4, and pointed to ongoing land-and-expand momentum: across the trailing four quarters from Q3-25 to Q2-26, the company added 13 new AI Infrastructure customer logos, and seven of those customers subsequently increased their business with it.
The Gap Worth Watching
PENG hit an all-time high of $89.86 on July 9, 2026. As of October 2, the stock closed at $61.36. That leaves it roughly 32% below its peak even as the business has continued to guide higher. The disconnect is the story going into Tuesday.
It may partly reflect margin anxiety. Q3 non-GAAP gross margin came in at 28.1%, and management flagged that Q4 pricing could be less favorable than Q3. Operating cash flow also turned negative as the company invested to support growth. Those are real friction points.
Risks Worth Pricing In
This is a high-beta stock, measured at roughly 2.85, meaning it amplifies both good and bad days in the market. The company is winding down its Penguin Edge business and moving away from hyperscale revenue, which creates near-term lumpiness. Supply chain lead times for certain components could slow project ramps. An interim CFO has been in place since July, which adds a thin layer of execution uncertainty going into a full-year close.
The Read-Through
Penguin Solutions may be the cleanest small-cap signal available on enterprise AI rack demand. Dell, HPE, and Super Micro all carry far more revenue diversity. Jabil has contract manufacturing complexity layered on top. Penguin, at roughly $3.1 billion in market cap, is narrow enough that its results speak almost directly to whether enterprises and neocloud operators are actually deploying AI infrastructure at the pace the hyperscalers have been telegraphing. Tuesday night will say a lot about whether that deployment cycle is still accelerating or beginning to plateau.
 Rising Star Stocks