S&P Global (SPGI) dropped its Q3 results at 7:15am ET this morning, with CEO Martina Cheung and CFO Eric Aboaf on the call at 8:30am. This is the first full quarter the company has reported as a four-division business, having completed the Mobility spinoff on July 1. The headline numbers matter less than one specific line: the renewal rate inside Market Intelligence.
Market Snapshot
AI adoption now has to outrun slower renewals in Market Intelligence, which grew just 6% last quarter compared to Ratings revenue rising 17%. That divergence is the fault line going into this morning’s call. Wall Street consensus called for EPS of $4.43, down 6.3% year over year, with revenue of $3.64 billion. The year-over-year revenue comparison reflects the smaller post-spin base, not organic deterioration, but the stock will not grant that pass if the subscription renewal data looks soft.
Stocks in Focus
SPGI enters the session with context that cuts both ways. On the positive side, management has highlighted a large refinancing need over the next several years, and it has pointed to hyperscaler issuance as a meaningful tailwind. That pipeline has kept Ratings the clear growth engine. Healthy debt issuance, supported by AI infrastructure investments, hyperscaler financing, and improving M&A activity, is expected to have fueled the Ratings segment.
On the risk side, management has said larger customers are stretching out renewals while they negotiate AI use and IP protection terms. Cheung has framed this as a near-term effect, but it puts pressure on the 5.5% to 7% Market Intelligence growth guide. That negotiation drag is not a new concern, but Q3 is the first clean read on whether it is getting better or worse.
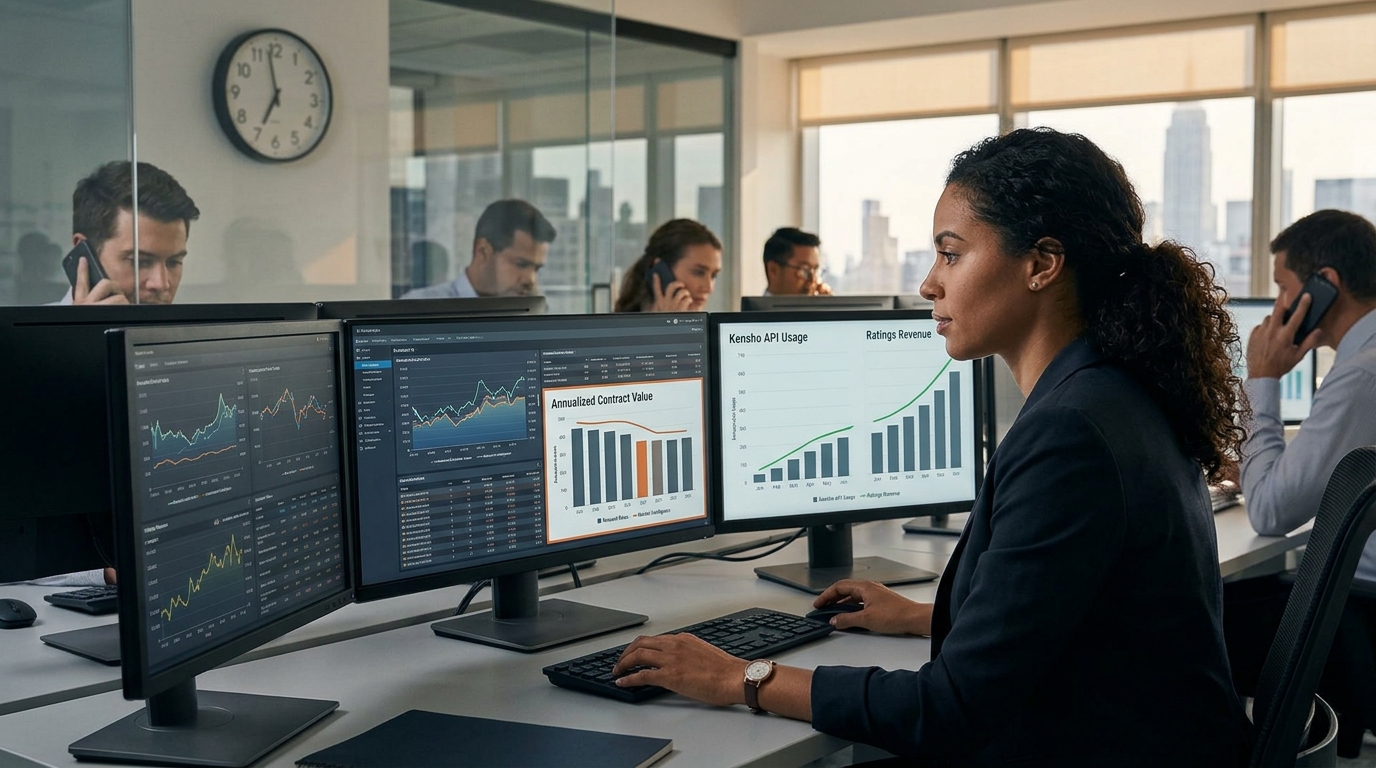
The AI metrics are real. Customers on LLM-ready APIs topped 500, up more than 70% from the prior quarter, and API call volume ran more than 5x first-quarter levels. Whether that usage turns into revenue is the open question: Kensho Data grows at a high single-digit to low double-digit rate, while Platforms grows in the low single digits.
Peers worth watching alongside SPGI: MCO (Moody’s) benefits from the same refinancing tailwind and will confirm whether credit ratings demand held across the sector. MSCI and ICE carry subscription model exposure similar to Market Intelligence. FDS (FactSet) is the most direct read on financial data renewal cycles.
Sector Watch
Financial data and analytics names have underperformed the broader market this year. That gap reflects the market’s skepticism about whether subscription businesses can convert AI enthusiasm into contract value at the pace the valuations require.
Risk Radar
Full-year adjusted EPS guidance stands at $17.50 to $17.75. The stock has little margin for error. Shares fell on July 28 despite solid Q2 results, as the newly issued 2026 adjusted EPS guidance and revenue growth outlook raised concerns about slower growth following the Mobility spinoff. A second guidance disappointment in two quarters would pressure the stock well beyond typical earnings-day moves.
The Cheat Sheet
- Top Theme: Ratings revenue is carrying SPGI while Market Intelligence negotiates its AI transition, and Q3 is the first quarter that tests whether that arrangement holds.
- Stock to Watch: SPGI. The 8:30am call is live now. Listen for Cheung’s characterization of renewal cycle length and any update to the Market Intelligence organic growth guide of 5.5% to 7%.
- Sector to Watch: Financial data and analytics. MCO, MSCI, and FDS will all trade on what S&P Global says about enterprise client behavior this morning.
- Biggest Risk: A third consecutive guidance trim would confirm that the subscription slowdown is structural, not cyclical, and reset the entire peer group.
- Biggest Opportunity: Management has cited early AI contract renewals coming in 35% to 45% above prior contract values. If Q3 shows that pattern broadening, the Kensho revenue story shifts from promise to proof.
- One Thing to Remember: Usage growth and revenue growth are not the same thing. Watch renewal rates, not API call volume, to decide whether today’s report is genuinely good news.
 Rising Star Stocks