The meeting six days away is not the story. The yield is.
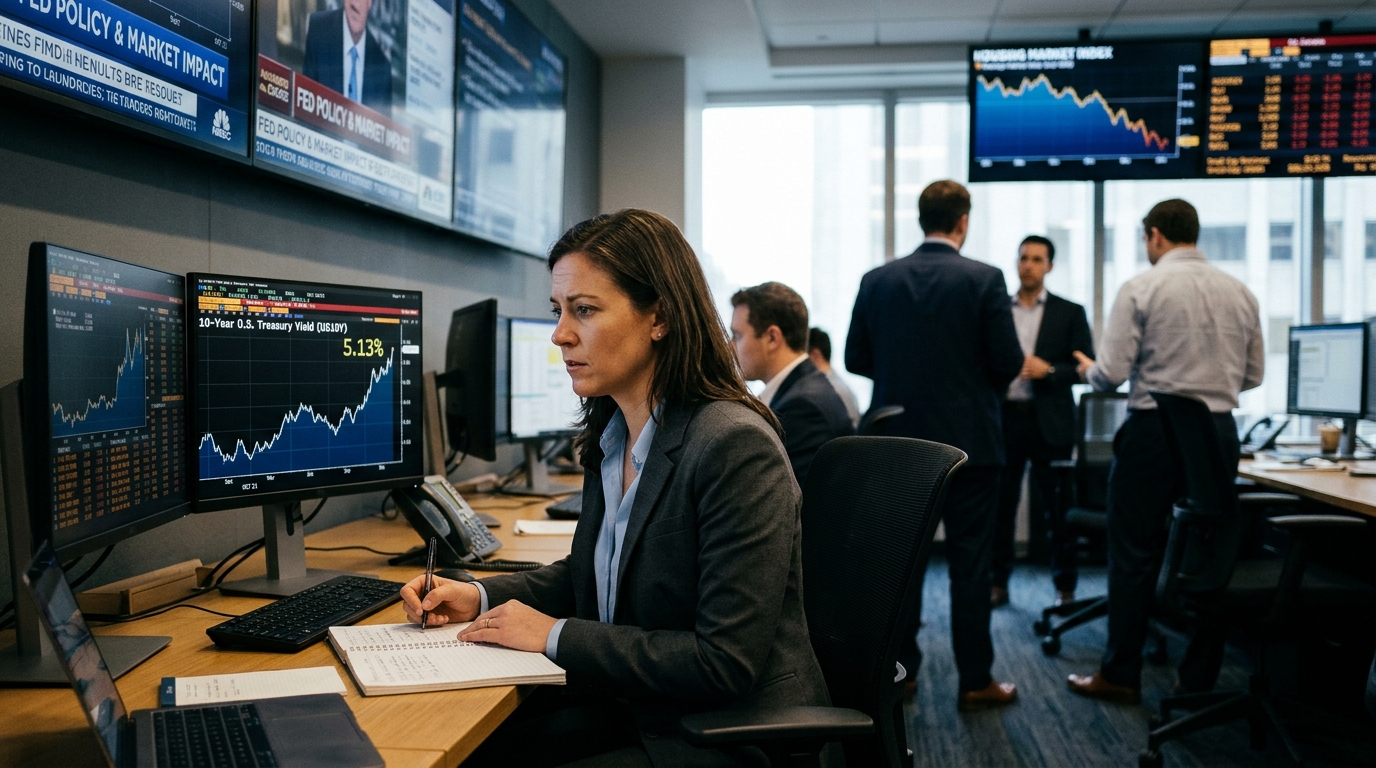
The 10-year Treasury closed at 5.13% on October 21, 1.18 percentage points higher than a year ago. That move did not wait for a Fed decision. It has been tightening financial conditions for months, and the damage is already visible in housing, small caps, and the lower rungs of the credit market, long before Kevin Warsh says a word on Wednesday the 28th.
What the Yield Is Doing Right Now
The 30-year fixed mortgage rate sits at 7.40%, 113 basis points above a year ago, and the driver is not the Fed’s policy rate, which actually fell 25 basis points over that same period. The mortgage rate moved with the 10-year almost basis point for basis point. Elevated mortgage rates reduce affordability, particularly when home prices remain high relative to household incomes, with effects extending beyond property transactions to construction, mortgage origination, household durables, and associated employment.
In September, 38% of builders slashed their prices, up from 35% in August, as they contended with sluggish demand due to rising mortgage rates. The iShares U.S. Home Construction ETF dropped last month, its worst monthly performance since July.
Small caps are taking a parallel hit. The Russell 2000 entered a technical correction this month as rising inflation and interest rates pushed the riskiest stocks below important averages, falling more than 10% from its most recent peak. The 10-year briefly touching 5.36% drove up corporate financing costs and disproportionately hurt smaller companies that carry more debt and rely more heavily on floating-rate borrowings. When yields ease slightly, the Russell bounces, it rose 45 points, or about 1.7%, on October 20, but that relief is conditional on the yield staying contained.
In credit, the picture is less alarming than the equity moves suggest, but the direction is clear. The high-yield spread was 3.29% on October 19, up about 25 basis points from a year earlier. CCC-and-lower option-adjusted spreads reached 12.78% as of October 15, sitting at the 100th percentile of their range since October 2023. The broad high-yield market has not cracked, but the weakest borrowers already have.
What the Fed Meeting Actually Decides
Kalshi and Polymarket put a quarter-point hike at about 12% and a hold at about 88% as of October 20. That consensus formed largely because Warsh gave it nothing to push against. Speaking at the IMF annual meetings in Bangkok, he gave little indication of whether the Fed would hold or increase rates at the October 28 meeting. Warsh’s comments sent October rate hike odds lower, even as odds of a December rate move ticked up.
Goldman Sachs concluded that alongside other recent FOMC participant comments, Warsh’s remarks indicate the committee is set to pause in October, while still expecting another move in December. CME Group’s FedWatch tool has pointed to markets keeping December very much live.
The October meeting is therefore a communication event. The real question is what Warsh says about December, and whether the language shifts enough to move the long end. His comment that events have broadly matched expectations leans slightly hawkish, since the September projections pointed to another hike this year, and oil remains a key input: fuel-driven inflation tied to the Gulf conflict is a key source of upside price pressure. Brent crude recently traded around $112 per barrel, adding fresh pressure to any assumption that energy-driven inflation is cooling.
What the Market May Be Missing
The crowd is watching October 28 for a hike or hold. The more consequential signal is whether Warsh offers any comfort on the pace of tightening beyond December. He has been explicit that he does not believe in forward guidance. Warsh has repeatedly expressed skepticism of guidance itself, on the grounds that it can anchor policymakers to a plan the data has already invalidated. That posture leaves the long end of the curve without an anchor, which means the 10-year level is set by energy prices, supply, and term premium rather than Fed communication.
The mechanism at 5.3% is self-limiting: higher yields tighten financial conditions, raise mortgage and corporate borrowing costs, and make equities less attractive, which eventually gives investors a reason to buy Treasuries. That dynamic produced the mid-October rally in TLT. The iShares 20+ Year Treasury Bond ETF surged 3.8% over six sessions through October 15, supported by falling Treasury yields and $2.15 billion in October net inflows. But TLT is still down more than 8% year to date.
What to Watch Next
Today’s jobless claims are the last labor data before the blackout period ends and the FOMC convenes. Any upside surprise in claims could push hike odds lower still and give the long end a brief reprieve. The more durable signal comes Wednesday: not the decision itself, but how Warsh characterizes inflation progress and whether December remains live in his words, not just in the market’s pricing. A yield that holds above 5.10% into year-end will keep doing its own tightening, independent of whatever the committee decides.
 Rising Star Stocks