A stock that spent most of 2026 as a falling knife just delivered a result that made every bear in the room uncomfortable. The Trade Desk reported Q3 revenue of $735.97 million on Monday evening, against a Wall Street consensus sitting around $650.89 million. That is an $85.11 million beat, the kind of number that tends to end arguments about whether a turnaround is real.
The stock told you something was coming. TTD closed regular trading up 15.47% on November 9, 2026 before the report even hit, then jumped in extended trading, according to Benzinga Pro data. That post-earnings surge lands on top of a share price that, as recently as mid-October, had lost roughly three quarters of its value over the prior year. The short base was substantial: as of October 15, 2026, about 83.14 million shares were sold short, representing 19.87% of the float. Monday night turned that positioning into a problem.
What Changed
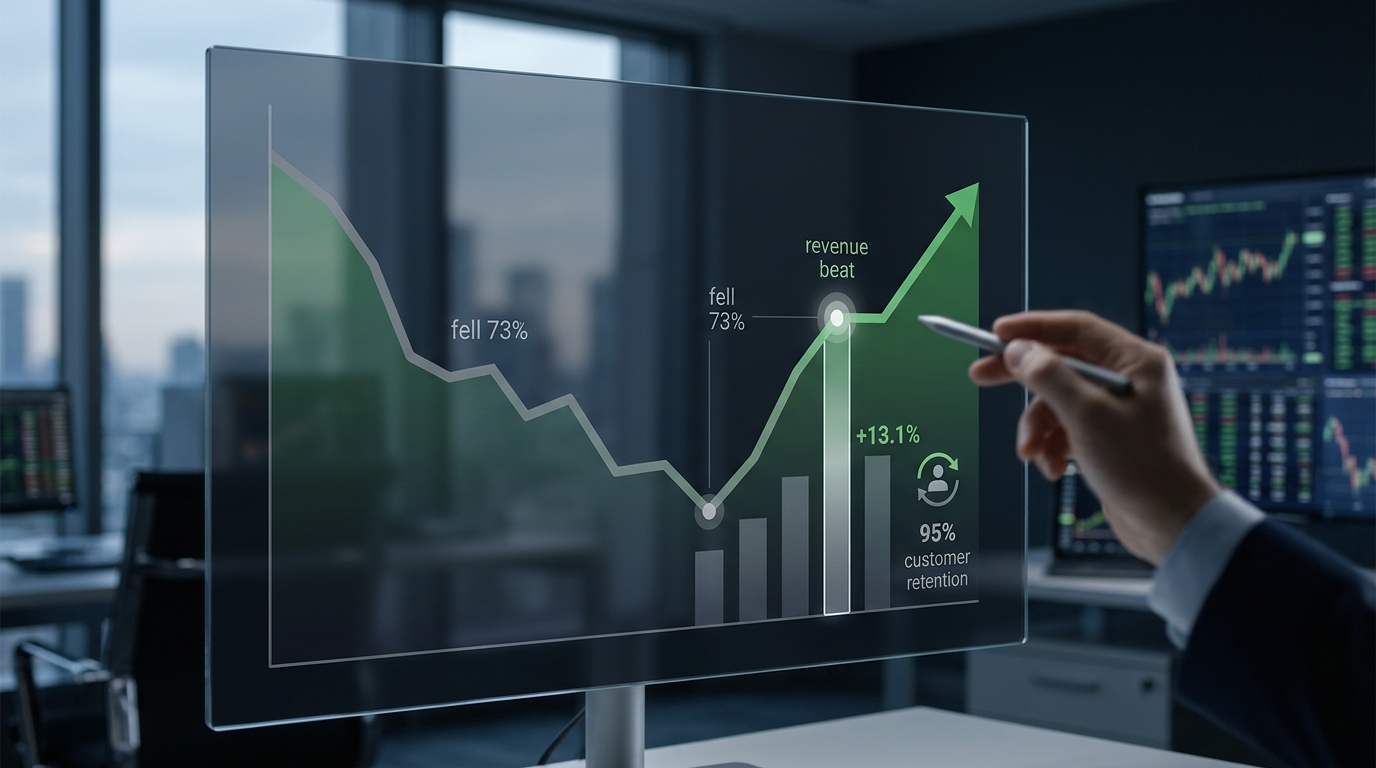
The Trade Desk delivered earnings and revenue surprises of 26.9% and 13.1%, respectively, with quarterly earnings of $0.33 per share beating the Zacks consensus of $0.26. On the top line, revenue beat estimates by $85.11 million, or 13.08%, with sales of $736 million versus the $650.89 million consensus.
The beats matter more in context. The size of the beat came after a period of softer growth and cautious expectations, making the result more of an execution beat than a return to strong growth. Just one quarter earlier, management had guided for a year-over-year decline in Q3, setting a low bar. When the guidance floor is that low and you clear it by about $85 million, the market moves accordingly.
Guidance for Q4 was equally constructive. Management expects revenue to be at least $755 million in Q4, versus analyst estimates of $685.38 million. Adjusted EBITDA guidance of at least $280 million was well above the $196.7 million consensus.
What Still Works
The retention number is the clearest argument that the business itself never broke. The company said customer retention remained over 95% during the third quarter, “as it has for over a decade.” When advertisers keep renewing through a year this ugly, it signals that The Trade Desk’s demand-side platform remains genuinely difficult to replace.
The CTV pipeline is also strengthening at an important moment. Netflix expanded its integration with The Trade Desk, enabling advertisers beginning in November to use both first- and third-party data to target audiences on Netflix through the Kokai platform, with in-platform measurement capabilities expected to follow. That opens a meaningful new inventory channel just as CTV programmatic buying becomes the default mode for brand budgets.
The board also authorized capital returns. As of September 30, 2026 the company had $269 million available for buybacks, and the board approved an additional $731 million, bringing the total authorized to $1 billion.
The Risks
Honesty requires flagging what the bulls are choosing to look past. Q3 revenue was down 0.5% year over year, which the company described as its first annual revenue decline since going public. Management also said approximately 3 percentage points of third-quarter revenue came from a strategic partner business not expected to recur, meaning underlying growth was actually negative. The company recorded about $44 million in restructuring charges tied to a September workforce reduction affecting roughly 15% of staff. Weakness in CPG and automotive advertising suggests some categories remain under macro pressure.
Competing against Amazon’s DSP is a different kind of challenge. Amazon’s pitch is first-party purchase data at scale, drawing on Prime membership and shopping signals. The Trade Desk’s answer is neutrality and open optimization, a compelling argument for large brand advertisers, but a harder sell with every quarter Amazon’s ad business grows.
What to Watch Next
The Q4 revenue floor of $755 million is now the number that matters most. If The Trade Desk clears it cleanly, the turnaround story graduates from a one-quarter beat to a trend. Watch whether the restructuring savings, projected by management at more than $100 million in gross savings in 2027, show up in margins. Watch the Netflix CTV ramp, specifically whether advertisers actually allocate new budget through Kokai rather than shifting from existing channels. And watch short interest, which sat at 19.87% of float as of October 15, 2026. With roughly 4.9 days to cover around that settlement date, any continued momentum will keep that covering pressure alive.
One quarter does not close a 73% drawdown. But execution that beats by about $85 million, retains 95% of customers through the worst year in the company’s public history, and pairs with a $1 billion buyback authorization is not noise. That is a business telling you it is still standing.
 Rising Star Stocks