September 16, 2026
Grab is buying into consumer credit, and the Atome deal explains why.
Grab has spent years telling investors it is more than a ride-hailing app. On Tuesday, it wrote the largest check yet to prove it.
Don’t sell your shares to him on Friday afternoon…
Every Friday afternoon like clockwork, a legendary trader scoops up shares knowing after-hours breaking news will have traders desperate on Monday morning to buy back from him for 5X… 10X… or even 100X what they sold for.
All the while he gets to collect as much as $9,518 OR MORE just for holding shares over the weekend.
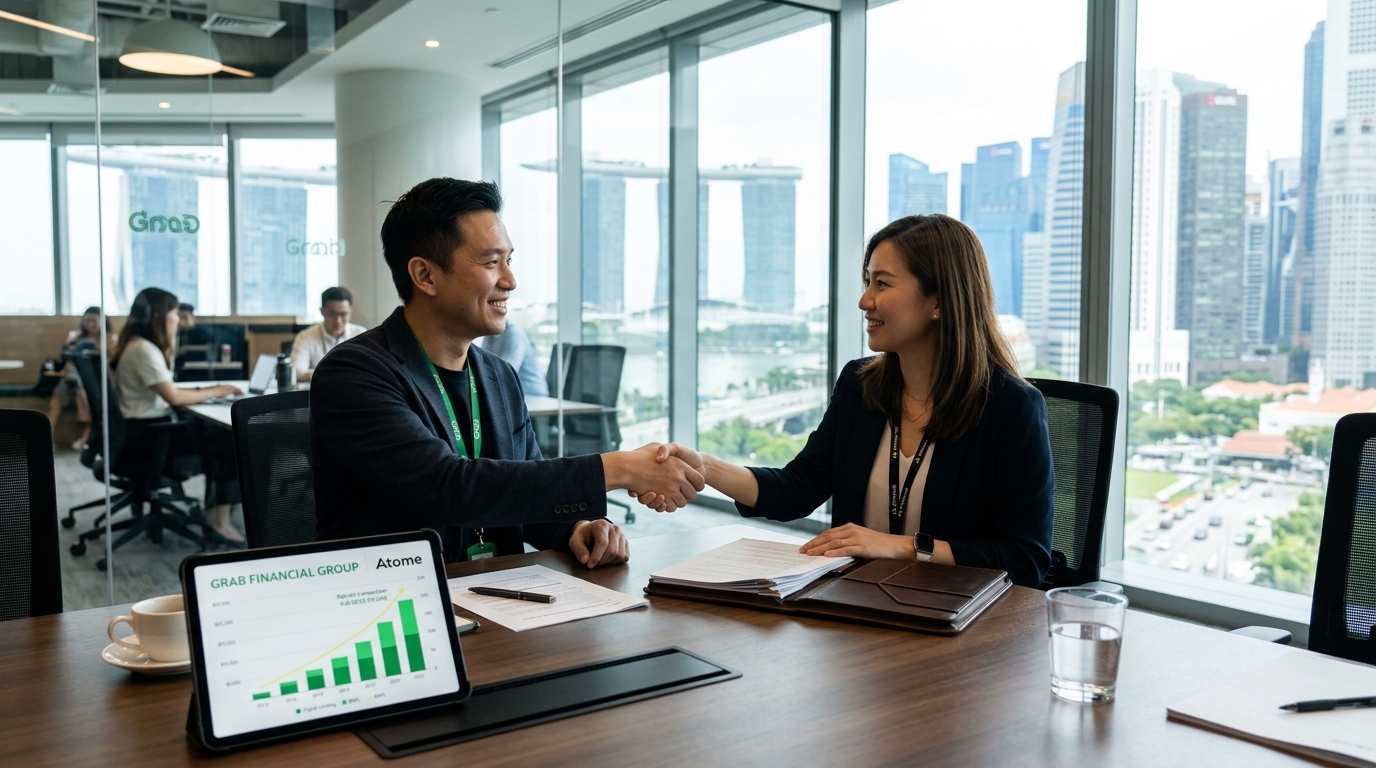
Grab announced it would acquire a controlling 60% stake in Atome Financial for $1.49 billion in cash, including $260 million in primary growth capital. The deal would combine Atome Financial’s business, spanning BNPL loans, consumer cash loans, BNPL cards and digital lending, with Grab’s financial services operation. The transaction is expected to complete by the third quarter of 2027, subject to regulatory approvals.
What Grab Is Actually Buying
Atome is not a startup with a vision deck. Atome Financial said it generated $470 million in revenue in FY2025, up 80% year over year, and it said it recorded its second straight year of pretax profit. Its flagship app has been recognized as Asia’s most popular BNPL app in the 2025 Sensor Tower APAC Awards, and the group also operates Kredit Pintar, a major Indonesian digital lending business.
Atome operates in Singapore, Malaysia, the Philippines, Indonesia and Thailand, serving 25 million cumulative transacted users. That footprint is the point. Grab already has the app on millions of phones across the region. What it lacked was a seasoned credit underwriting engine and an established merchant base. Atome brings both.
The Distribution-Meets-Credit-Data Thesis
Grab’s gross loan portfolio reached $1.438 billion as of Q1 2026. The combined business is expected to carry a gross loan portfolio of more than $6 billion by 2028. Grab has said Atome Financial has a gross loan book of over $1 billion today. Quadrupling the portfolio in under three years is an ambitious target, but the arithmetic is not unreasonable when you layer Atome’s credit rails onto Grab’s transaction volume.
Most Options Courses Start in the Wrong Place
Most beginner options courses lose people in the first lesson. Greeks. Spreads. Implied volatility. It doesn’t have to be that way. This free guide starts with the basics first-so you can finally understand how options work before risking real money.
Last year, 68% of Grab’s driver-partner borrowers used the company to access formal credit for the first time, with half saying they did so to avoid unlicensed lenders. That behavioral data is worth as much as the loan book itself. Grab knows who its users are, where they go, how often they spend, and whether they tip. Atome’s AI-powered underwriting can plug directly into that signal.
Grab’s CFO Peter Oey described Atome as giving the company a proven consumer lending operator and an established merchant base, adding that the transaction is funded entirely from existing cash and is expected to be accretive to Group Adjusted EBITDA upon completion.
The Numbers Grab Is Chasing
Grab raised its overall 2028 Adjusted EBITDA target to $1.7 billion and now expects annual revenue growth of more than 30% between 2025 and 2028. The financial services segment alone, including Atome, is targeted to generate $500 million in Adjusted EBITDA by 2028.
Context matters here. Grab’s financial services segment posted an adjusted EBITDA loss of $17 million in Q1 2026. The company is betting $1.49 billion that a proven external operator accelerates a turnaround faster than internal scaling ever could.
That kind of bet — paying a premium today for profitability that has not yet arrived — is a pattern worth examining across the tech landscape. a critical look at how investors are pricing loss-making tech platforms ahead of major liquidity events raises questions that apply equally here: at what point does scale justify the losses, and who bears the risk if the turnaround takes longer than the model assumes?
Where the Risk Lives
The loan book is also the liability. BNPL providers have faced growing scrutiny in multiple markets over unsecured lending and consumer protection, particularly as installment products spread to younger and thinner-file borrowers. Grab is not just buying growth; it is putting consumer credit risk onto its own balance sheet at scale.
5 Little-Known Stocks Behind Today’s Defense Tech Shift
Behind the headlines, a major transformation is underway.
Modern warfare is being driven by AI, autonomous systems, and next generation technology. A handful of lesser known companies are helping power this shift.
This report uncovers five stocks quietly playing a critical role in the future of defense.
GoTo, Grab’s primary rival in Indonesia, has been building its own financial services capabilities through GoPay and its Bank Jago partnership. Sea Limited is pushing in a similar direction. The competitive pressure may justify the urgency. It does not eliminate execution risk in a macro environment where credit quality can shift faster than underwriting models update.
The Bigger Picture
About 1.3 billion adults globally remain unbanked, and Southeast Asia, especially Indonesia, still represents a significant portion of that gap, particularly among rural, lower-income and informal workers. That is the long-run opportunity Grab is positioning for.
Grab has also agreed to purchase the remaining 40% of Atome Financial approximately two years after the initial transaction closes, with the Phase 2 price tied to Atome’s actual performance rather than a fixed valuation. Grab has said the resulting equity valuation for that tranche is subject to a floor of $2.0 billion and a cap of $4.5 billion. That structure keeps Grab disciplined while rewarding Atome’s team for what they build after the deal closes.
Grab is no longer pitching a future in financial services. It just paid $1.49 billion for one. Whether the loan book performs is the question worth watching.
 Rising Star Stocks