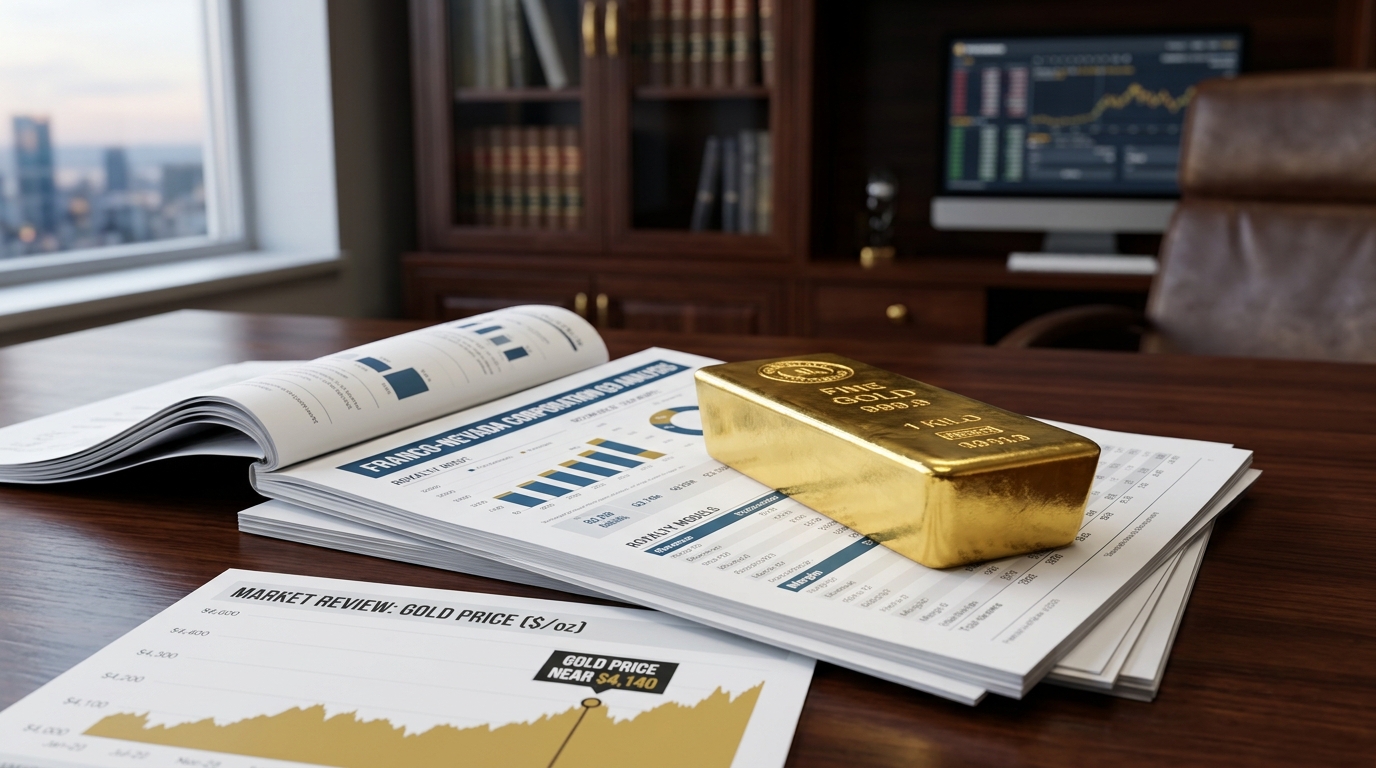
Back in the 1860s, settlers from France, Italy, and Germany built grand Parisian boulevards…
…neoclassical facades…
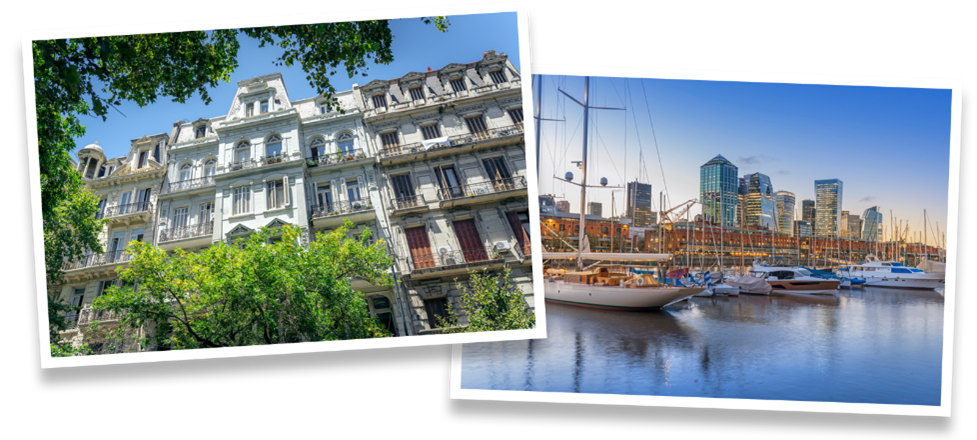
… and cobblestone Bavarian villages halfway across the globe.
Then the rest of the world largely forgot about them.
Today, expats are uncovering a European standard of living…
… Lakefront rental homes for $721 a month…
… private chauffeur service…
… and elite healthcare – completely free from tourist crowds and inflated European price tags.
Gold Is Near $4,140. Franco-Nevada Keeps the Upside.
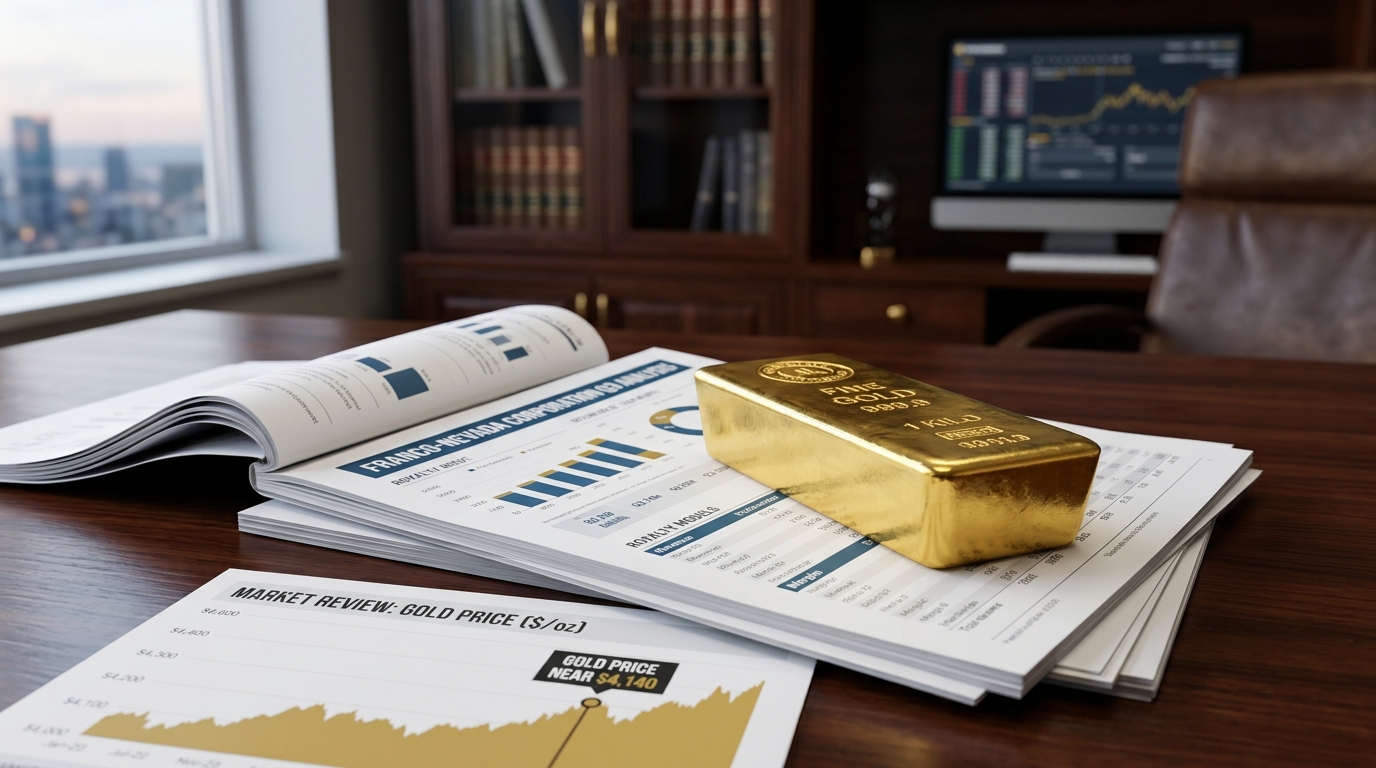
Gold closed near $4,140 on November 9. That is not an accident for Franco-Nevada shareholders. It is a revenue line.
The company reports Q3 2026 results after the close on Tuesday, November 11. Analysts are looking for $1.77 per share on roughly $568 million in revenue. That consensus implies a meaningful step down from the first half, when Q1 delivered a record $650.7 million and Q2 added another $580.9 million on a 57% year-over-year revenue surge. The question heading into Tuesday is not whether the royalty model works. It clearly does. The question is what a gold price that bottomed near $3,900 in late October and then clawed back above $4,130 in the first week of November actually means for the quarter’s realized average.
The Margin Machine
Franco-Nevada does not operate mines. It finances them in exchange for a slice of future output or revenue, then collects a check every quarter with no exposure to labor costs, energy inflation, or capital overruns at the mine site. When gold rises, almost all of that gain flows straight to the bottom line.
In Q2, adjusted EBITDA margin reached 91.2%. In Q1, net income more than doubled year over year to $468.6 million on volume that was only 8% higher. The operating cost base barely moved: cost of sales rose from $38.5 million to $46.5 million even as gold prices jumped from prior-year levels. Per gold equivalent ounce, margin expanded 179% since 2022 while gold itself rose about 160%. The royalty structure amplifies commodity price moves rather than absorbing them.
The Portfolio Keeps Growing
Franco-Nevada has not been passive. Early in 2026, the company deployed over $500 million in fresh capital, including a $250 million net smelter return package on i-80 Gold’s Nevada assets and an A$170 million gross royalty on the Bullabulling project in Western Australia. In September, it went back to Bullabulling with a follow-on A$200 million financing that lifted its gross royalty there to 3.90%. In October, it took about a 12.4% equity stake in Kenorland Minerals, which holds a 4% net smelter return royalty on the Frotet project in Quebec.
Management’s 2026 guidance targets 510,000 to 570,000 gold equivalent ounces, a range that deliberately excludes any contribution from the idled Cobre Panama mine. Each new royalty added this year extends the production profile without adding a dollar of operating risk.
The contrast with conventional miners sharpens the royalty case. Barrick’s Q2 showed how rising all-in sustaining costs can swallow a production beat and compress free cash flow even as gold prices climb.
What Tuesday Needs to Show
The honest risk here is gold’s own volatility. The metal spent much of October near a one-year low before recovering sharply. If the Q3 realized average came in well below $4,500, the consensus could prove optimistic. FNV missed both earnings and revenue estimates in Q2.
That said, the structural story has not changed. CPM Group has said gold investment demand may reach 66.7 million ounces in 2026, more than double 2023 levels. Reuters reported after the election that Democratic wins in the midterms weakened the dollar into early November. Gold is trading near $4,120 this morning and holding its session high.
Tuesday’s report will not rewrite the thesis. But it will tell you how much of this year’s extraordinary gold price environment actually landed in Franco-Nevada’s royalty checks, and whether the margin expansion that defined Q1 has legs into the second half.
That is worth watching closely.
 Rising Star Stocks