September 23, 2026
Bonus Content: SoFi Just Settled $25 Billion in Card Payments on a Blockchain
Dear Income Seeker,
If you’re struggling to find high-probability income trades…
Or think you’ve found them…
Only to be frustrated – and disappointed – with the money you’re bringing in…
You owe it to yourself to check out this website.
Because it will give you the opportunity to get your hands on a little-known 1-hour trading secret… 100% free of charge.
Do your future self a big favor and claim a copy now.
Because at some point soon, it won’t be free.
To better trading,
– Drew Day
Partner
Base Camp Trading
SoFi Just Settled $25 Billion in Card Payments on a Blockchain
The payments industry has spent years talking about blockchain settlement. SoFi just did it.
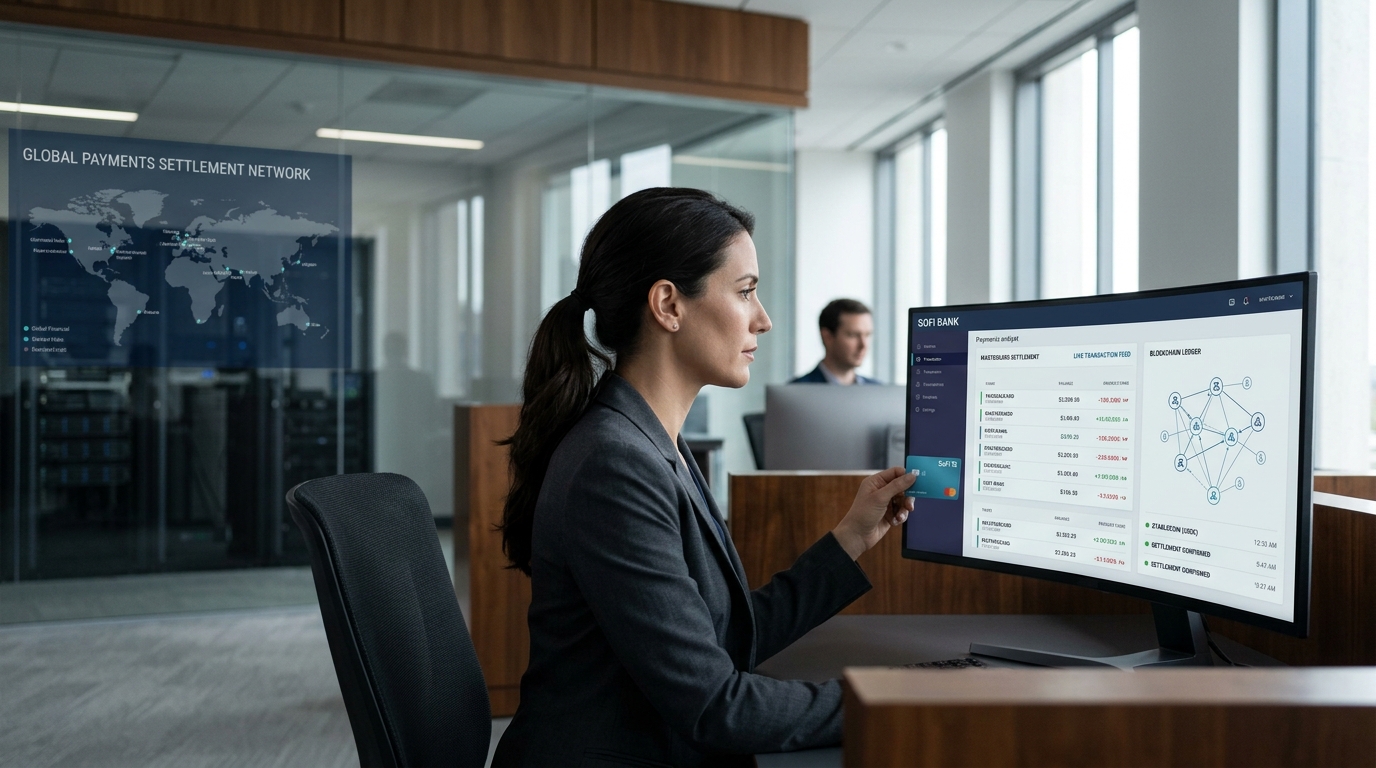
On Tuesday, SoFi Technologies (SOFI) and Mastercard (MA) announced that stablecoin settlement is now live across SoFi Bank’s full debit and credit card program. SoFi Bank said it is migrating its full card program to blockchain-based settlement using SoFiUSD, with the program expected to process more than $25 billion in annualized volume. This is not a pilot. Transactions are running on-chain today.
What Actually Changed
SoFi said SoFiUSD is the first stablecoin issued by a nationally chartered bank, and that SoFi is the first national bank to go live with stablecoin settlement across Mastercard’s network. That combination of federal charter and global network scale is the detail that separates this from the wave of crypto-adjacent payment experiments that preceded it.
SoFi launched SoFiUSD in December 2025, saying that because the stablecoin runs on a public, permissionless blockchain, partners can move money 24/7 with near-instant settlement at fractional-cent pricing. The card program migration puts that claim under real commercial volume for the first time.
CEO Anthony Noto’s pitch to merchants is deliberately frictionless. Merchants do not need to hold SoFiUSD or change their existing payment systems. Through the Big Business Banking platform, they can receive instant settlement funds in a SoFi Bank account and withdraw them as cash around the clock at no cost. Traditional card settlement can take longer to actually land in a merchant’s account, even though the purchase is authorized in seconds. Stablecoin settlement collapses that gap, and the fractional-cent cost structure is positioned as a way to reduce friction merchants and banks normally absorb.
The Valuation Question
Here is where it gets interesting for investors. SOFI recently traded around $17, with a market cap roughly around $22 billion. In SoFi’s Q1 2026 materials, the company reported a 58% Lending segment contribution margin. The market prices SOFI accordingly, with many analysts rating the stock a Hold and average targets clustering around $20.
But the stablecoin launch introduces a different business line entirely. Payments operators can command higher revenue multiples than lending platforms. The gap between those two multiple profiles is the bet embedded in this announcement.
The companies also outlined plans to offer the settlement option to other issuing banks through SoFi’s Galileo technology platform, which means the addressable opportunity extends well beyond SoFi’s own card volume. SoFi said it is already in active discussions with large merchants across the U.S. regarding stablecoin-based settlement arrangements. Galileo as a B2B distribution channel for bank-issued stablecoin settlement is a meaningfully different revenue story than personal lending.
Piper Sandler analyst Patrick Moley has initiated coverage at Overweight, arguing that SoFi deserves a premium multiple to peers. The stablecoin launch gives that call a harder operational foundation than it had before.
Risks Worth Watching
The revenue contribution from crypto and stablecoins remains small. SoFi has disclosed net crypto transaction revenue at under $1 million in Q1 2026 and about $1.2 million in Q2 2026. That small base helps explain why crypto developments can influence sentiment without immediately changing the company’s financial profile. Moving $25 billion in card volume to blockchain rails is operationally significant, but it does not automatically generate new fee revenue unless merchants adopt the Big Business Banking platform at scale and Galileo lands meaningful external bank clients.
Revenue growth has come alongside fast-growing expenses, and SoFi could still struggle to expand its operating margins without sacrificing growth. That tension does not disappear because the settlement layer changed.
The Bigger Picture
Mastercard’s incoming CFO Ling Hai said on Sept. 10 at the Goldman Sachs 2026 Communacopia + Technology conference that stablecoin and digital asset infrastructure represents an opportunity for growth, and that the company is embedding stablecoin orchestration and white-label wallet capabilities directly into its payments stack. SoFi is the first live proof point in that strategy, which gives both companies incentive to make the merchant adoption numbers work.
SoFi is not the only company betting that stablecoin rails can become a durable payments business. Circle, the issuer of USDC, has been making a similar case to investors, though its path to fee revenue faces its own structural questions. For a closer look at how the market is pricing that thesis and where the skepticism lies, this breakdown of Circle’s Q2 earnings and the valuation challenge facing USDC as a payment rail offers a useful point of comparison for anyone tracking the competitive landscape in bank-grade stablecoin settlement.
The real test is whether Anthony Noto can convert a genuine infrastructure first into durable fee revenue at a scale that closes the gap between SOFI’s lending multiple and the payments multiple it is now reaching for. The plumbing is live. The business case is next.
 Rising Star Stocks