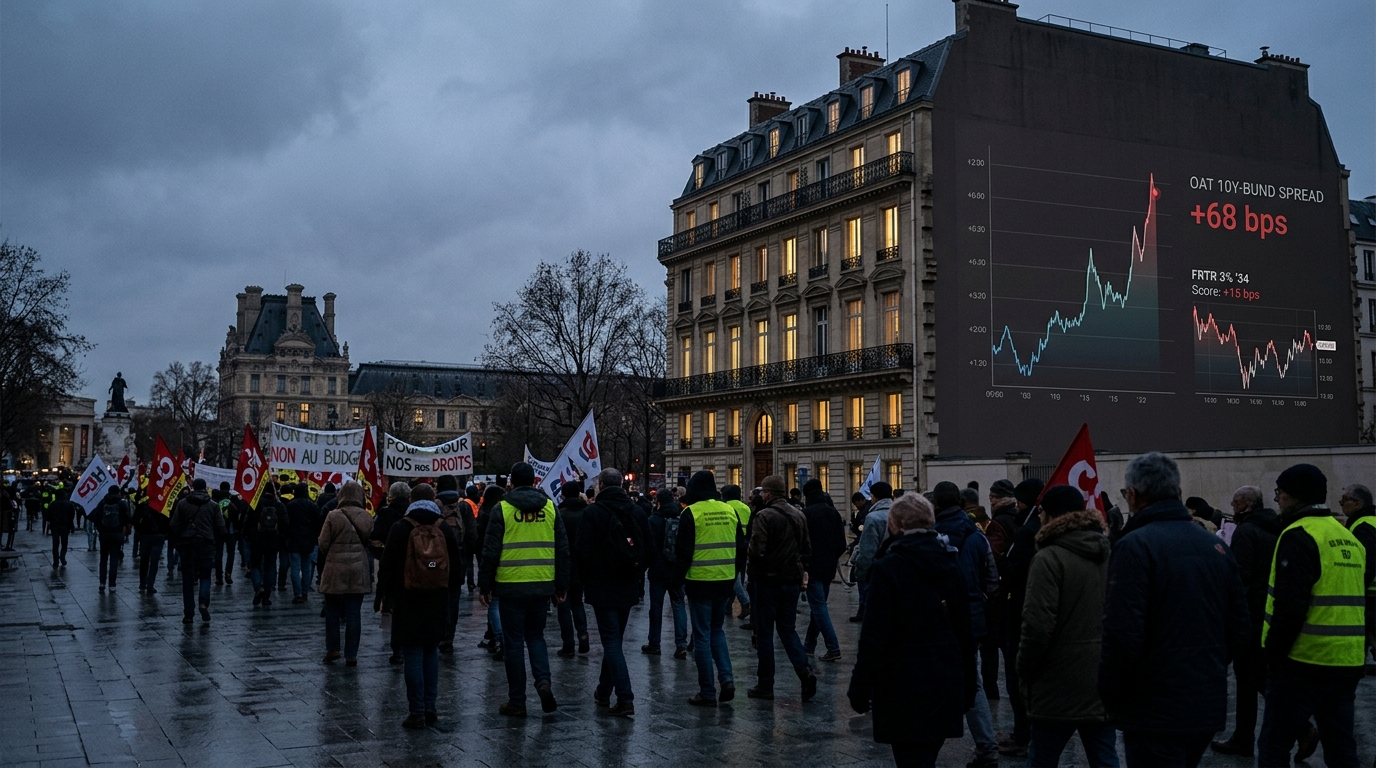
The question that will define European markets this week is not whether France is in trouble. It is whether the trouble stays French.
The French Interior Ministry said around 550,000 people took part in Saturday’s protests, including roughly 110,000 in Paris. The social movement has gained cross-class, cross-working-sector support, uniting groups including remnants of the yellow vests, the grassroots cost-of-living protests that shook France in 2018. In Lyon, protesters set fire to a tourism office, while groups of hooded youths threw projectiles and fireworks mortars at police, who responded with tear gas and water cannons. Prime Minister Sébastien Lecornu said 150 police officers and gendarmes were injured. Authorities arrested more than 1,200 people, mostly in Paris.
The streets are the symptom. The bond market is the diagnosis.
What the OAT Is Telling You
As of October 16, the OAT-Bund spread stood at 137.4 basis points, up 2.2 basis points from the prior session, reflecting a significant risk premium on French debt. The 10-year OAT yield has climbed to around 4.8%, briefly nearing 5%, its highest level since 2008, and it was set for its biggest quarterly increase since 1987. The benchmark French 10-year yield has risen sharply this year, according to Reuters reporting citing LSEG data.
Those numbers were priced before Saturday. Monday’s open is the first chance for the market to react to the weekend’s images: a tourist office burning in Lyon, city halls breached in Marseille and elsewhere, and a protest count that the interior ministry itself put at over half a million.
Lecornu has put forward a 2027 budget that would trim the deficit to 5% of GDP from 5.4%, with the parliamentary process already under way in the National Assembly, beginning with the revenue section. The adjustment amounts to about €54 billion. A straightforward parliamentary agreement appears unlikely given the absence of a stable majority. The more plausible route is that several weeks of negotiations produce a modified budget, but without enough support for a formal vote. The government could then use Article 49.3 of the constitution, which allows it to pass the bill without a formal vote, unless an absolute majority of MPs vote to bring down the government.
Where It Shows Up Beyond the OAT
Analysts at ING warned that the market could “easily add another 2% in risk premium to the euro” if the bond sell-off extended. The euro has already felt the pull: French debt troubles helped push the common currency to a 17-month low against the dollar, as fiscal and political risks in Paris revived memories of the eurozone debt crisis.
French bank stocks are the other transmission channel. Banks had been Europe’s best-performing stocks for two years and were on pace for strong gains again in 2026, but the return of French debt worries is threatening to derail the rally. Société Générale has fallen about 25% from its August peak. France accounts for about a quarter of BNP Paribas’s revenue, while Société Générale and Crédit Agricole have higher exposure. That distinction matters: BNP’s geographic diversification gives it more insulation, but neither name escapes the sovereign’s gravitational pull when spreads move this fast.
Is This Staying in France?
For now, the stress appears contained within France. Banque de France Governor Emmanuel Moulin recently said the solution is not to seek answers in Frankfurt, attributing France’s higher borrowing costs to its deficit and uncertainty over the budget vote rather than to a breakdown in euro-area markets.
One strategist noted that French bank CDS spreads remain below France’s sovereign CDS, a sign of better capitalization than 15 years ago. “This is very different from the euro sovereign debt crisis when bailing out banks had triggered a doom loop with public debt,” he said. That is a meaningful structural difference from 2011. But it is not a ceiling on how wide the spread can go before the argument breaks down.
ING strategists forecast the OAT-Bund spread will sit between 100 and 125 basis points in the coming months, while the European Central Bank may be unwilling to step in with bond purchases while it remains focused on inflationary pressures. That assessment predates Saturday’s unrest.
What to Watch Next
The budget’s next votes in the National Assembly are the immediate test. Macquarie strategist Thierry Wizman argued that a series of convulsions would have to occur for France to appease the bond market, potentially including a no-confidence vote, a Moody’s credit downgrade, a sharper contagious spike in France’s bond yield spread, or the election of Le Pen as president. Moody’s currently holds France at Aa3 with a negative outlook, which means a downgrade is already on the table without any additional shock.
Watch the OAT-Bund spread on Monday’s open. If it holds near 137 basis points, the market is treating Saturday as noise. If it pushes back toward 150, a level reached earlier this month, the question of containment becomes harder to answer.
 Rising Star Stocks