Meta’s Q3 report landed two days ago and left a bruise the market has not yet recovered from. Meta’s stock fell about 7%, the semiconductor index plunged 6.7%, and the Nasdaq dropped 2.6% in its worst day since June. The immediate catalyst was negative free cash flow, not bad revenue. Meta spent about $34.9 billion on data centers and equipment in the quarter, more than the $32.8 billion of cash its operations produced, so free cash flow was negative $2.1 billion. Then came the forward guidance that made it worse: 2026 capital expenditures, including principal payments on finance leases, are now forecast at $135 to $145 billion, narrowed from the prior outlook of $130 to $145 billion.
That is the context for what arrives in 48 hours. Microsoft and Alphabet report October 28. Amazon and Intel follow October 29. These four reports land alongside a Fed decision and days before the September PCE reading, into a market that has already decided AI spending is a problem and is waiting to be told otherwise.
Why Investment Committees Are Focused Here
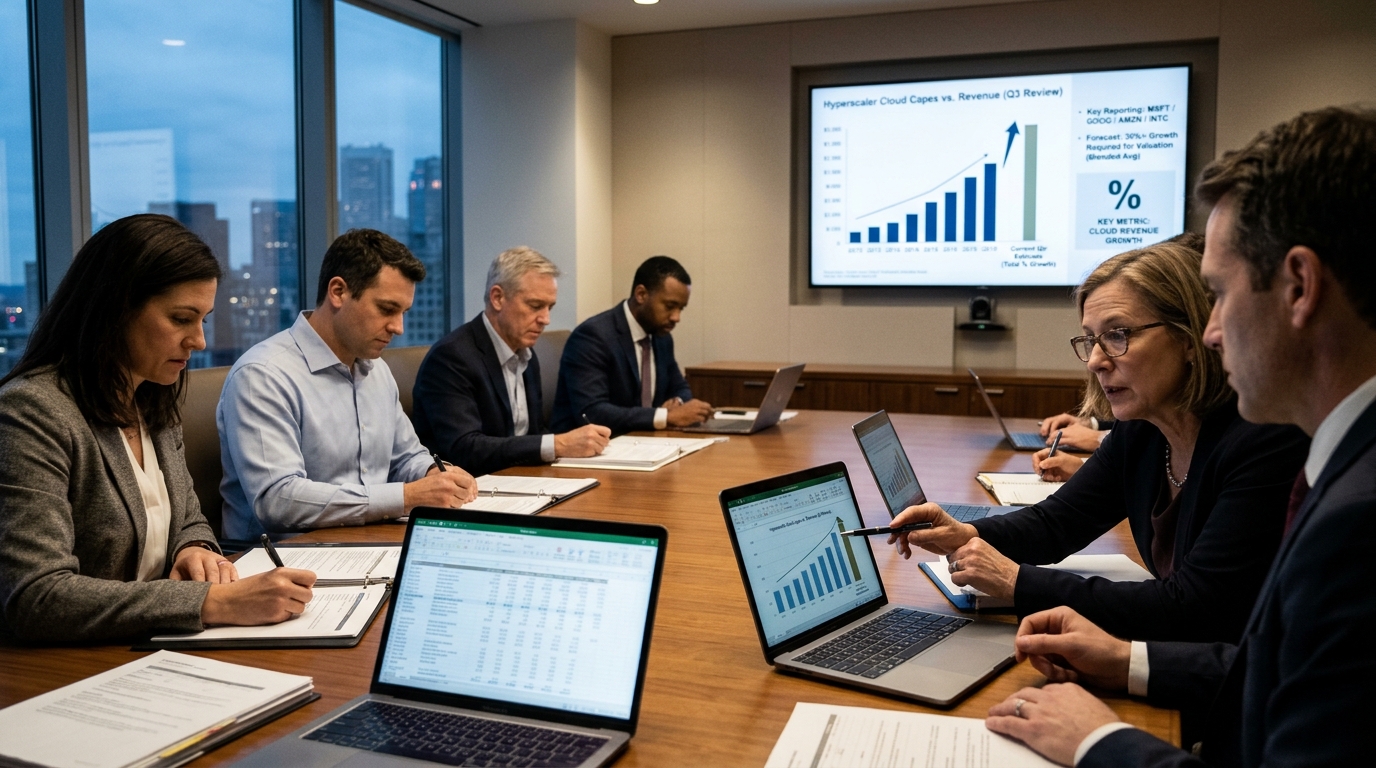
The central question is not whether these companies are profitable. The blended earnings growth rate for the S&P 500 in Q3 2026 is 29.5%, up from 29.2% last week. Earnings are fine. The question is whether cloud revenue is growing fast enough to convert hundreds of billions of annual capital spending into returns before the cycle turns.
Combined 2026 capex across Amazon, Alphabet, Microsoft, and Meta is guided at roughly $730 billion, up 78% from $410 billion in 2025. Amazon leads at approximately $220 billion, Alphabet at $195 to $205 billion, and Microsoft near $175 billion. Goldman Sachs has quantified what those sums require: assuming a 15% annualized return on invested capital, these hyperscalers would need to generate cumulative revenues of approximately $1.42 trillion between 2028 and 2030. The clock on that obligation is now running.
The Bull Case
The most recent cloud data is genuinely strong. Google Cloud reported an 82% year-over-year revenue jump in Q2 2026, hitting $24.8 billion, while AWS grew 37% and Azure grew 43%. Microsoft’s Azure crossed $100 billion in annual revenue for the first time during fiscal 2026, and commercial remaining performance obligations reached $627 billion, with approximately 30% expected to convert to revenue in the next twelve months. That backlog is the structural argument: this spending is chasing committed demand, not speculative capacity.
Microsoft’s fiscal Q1 report, due October 28, is expected to show Azure growth of roughly 45% in constant currency, with consensus at $4.72 a share on $90.69 billion in revenue, and capital spending set to exceed $50 billion in the quarter. If Azure holds near that rate and the capex number does not shock further, the bull case stays intact.
The Bear Case
The bear case is a margin story, and it has been building for three quarters. Microsoft’s gross margin compressed for a third consecutive quarter, from 69.1% to 68.0% to 67.6%, as capex tracked toward $190 billion for calendar 2026. Goldman analysts expect return on equity across the largest technology companies to decline by an average of seven percentage points next year as spending on data centers and computing infrastructure continues to accelerate. The spending does not stop when the market gets nervous. It compounds.
Amazon’s situation has a specific wrinkle. Amazon Web Services offers a view of both the consumer and AI, through retail demand and cloud growth, but Amazon’s trailing free cash flow turned negative earlier this year, so the same spending questions that hit Meta apply. AWS grew 37% in Q2, its fastest rate in 18 quarters, yet Amazon still lost ground in cloud market share because the overall market grew faster.
The Mavens’ View
The market is not actually debating whether AI spending will continue. It is debating who gets to keep increasing it without paying a stock price penalty. Meta spent more than it earned in a single quarter and the market sold it down 7%. Microsoft spent $3.4 billion less than analysts expected in Q3 and the stock fell anyway, because management then disclosed $190 billion in 2026 calendar capex. The threshold for what counts as reassuring has moved considerably tighter.
The distinction investors are drawing is between companies whose cloud revenue growth visibly exceeds their capex growth, and those where the gap is closing or gone. Alphabet’s 82% Google Cloud growth in Q2 beat its 120% capex increase on a dollar basis, but only barely. Google Cloud’s 82% growth is the stronger absolute number, but Azure’s 44% growth, which came with flat capex guidance, was the stronger market signal. Investors right now are not rewarding the highest growth rate. They are rewarding efficiency signals.
What Investors Are Missing
Intel’s report on October 29 is getting less attention than it deserves. Last quarter, Intel’s revenue rose 25% to $16.1 billion, its fastest growth in about 15 years, with data center sales jumping 59% and adjusted earnings coming in at double what analysts expected. The company is a direct beneficiary of inference-oriented AI data centers, which are shifting their CPU-to-GPU ratio toward parity. Reports that Intel has implemented cumulative CPU price hikes of 30% in 2026, with the latest increase on October 5, are not confirmed in Intel filings and should be treated as market chatter until management substantiates it. If Intel’s Q3 report confirms that server CPU demand is still outpacing supply and guidance moves the right direction, it provides a different kind of AI infrastructure signal than the hyperscalers: one that does not require $200 billion in annual spending to deliver.
Stocks to Watch
Microsoft (MSFT). The single most important report of the week. Azure’s growth trajectory and the Q1 capex figure together will reset the market’s view of whether the AI spending cycle has crested or is still building. A capex overshoot against the already elevated $50 billion guidance would be poorly received.
Alphabet (GOOGL). Google Cloud’s 82% growth in Q2 was exceptional, but Alphabet paid for it: Q2 alone consumed $44.9 billion in capex. The Q3 report will show whether that pace moderated and whether Cloud revenue held above $24 billion. Both matter equally.
Amazon (AMZN). Amazon reports October 29 and offers a simultaneous read on the consumer and AI, through retail demand alongside AWS growth, margins, and capital spending. AWS guidance for Q4 will carry more weight than the Q3 result.
Nvidia (NVDA). Does not report this week, but the combined spending disclosures from all four companies function as a proxy read on Nvidia’s forward demand. Goldman Sachs has projected hyperscaler capex around $1.2 trillion in 2027. If that trajectory holds in guidance language, Nvidia remains the most direct beneficiary.
Intel (INTC). The overlooked name. A clean beat with strong Q4 server CPU guidance would make the case that AI infrastructure benefits are broadening beyond the hyperscalers themselves, and that Intel’s recovery is real rather than priced in.
 Rising Star Stocks